
Founder Equity Dilution Explained for Early-Stage Startups
For early-stage startups, dilution is not a side issue; it is one of the central mechanics of building a company. Every new financing round, option grant, advisor allocation, or strategic hire can change how much of the business founders ultimately own and control. That does not automatically mean something has gone wrong. In many cases, dilution is the cost of turning an idea into a fundable, scalable company. The real question is whether founders understand what they are giving up, why they are giving it up, and how those decisions affect both incentives and long-term outcomes.
This matters especially in the earliest stages, when ownership percentages can look deceptively large and the consequences of each decision are easy to underestimate. A founder who owns 100% on day one may still end up with a minority stake after a seed round, an employee option pool refresh, and a few subsequent financings. That outcome can still be perfectly rational if the company is growing quickly and the value created is far greater than the ownership percentage surrendered. The challenge is to distinguish productive dilution from avoidable dilution, and to make those choices with a realistic view of fundraising, hiring, and control. For more ace context on startup strategy and capital formation, it can help to compare these trade-offs with key knowledge in founders, investment, and business.
What dilution actually means
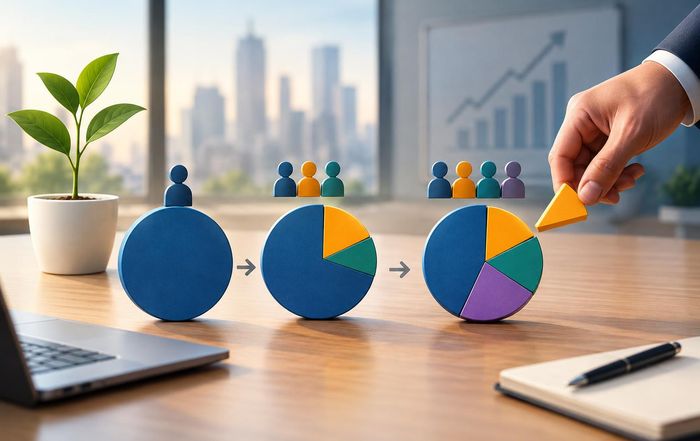
Dilution occurs when a founder's percentage ownership falls because the company issues new shares or equity-linked securities to someone else. The founder may still own the same number of shares, but those shares represent a smaller slice of the company after the new issuance. In startup finance, that usually happens when the company raises capital from outside investors, creates or expands an employee stock option pool, or issues equity as part of a strategic transaction. The dilution is mathematical, but its business effect is strategic: ownership becomes more distributed, and the balance of incentives changes.
It is important to separate percentage ownership from economic value. A founder can be diluted from 80% to 40% and still become much wealthier if the company's valuation rises substantially. That is why dilution should not be judged in isolation. The relevant question is whether the capital or talent gained in exchange is likely to increase the company's total value enough to justify the reduced ownership. This is one reason early-stage founders spend so much time on cap tables, term sheets, and option pool sizing; small changes at the beginning can compound over time. For readers following the broader financing environment, the relationship between startup ownership and capital markets is often shaped by conditions in stock markets, economy, and banking.
Why early-stage founders get diluted so quickly
Early-stage companies usually have little revenue, limited operating history, and high execution risk. Because of that, outside capital tends to arrive in exchange for meaningful ownership. Investors are not just funding a product; they are pricing in the uncertainty that the company may fail, pivot, or require more capital than initially expected. Founders often accept dilution because without outside money they may not be able to hire, build, or market fast enough to compete. In that sense, dilution is often the bridge between a promising concept and a viable company.
Employee equity also creates dilution, and it is often underestimated by first-time founders. A startup that wants to hire experienced engineers, product leaders, or commercial talent may need a meaningful option pool to compete with larger employers. That pool is not "free" equity; it is usually carved out of the same total ownership base that founders and investors share. In practice, this means founders may be diluted even before a major financing round closes. For companies operating in competitive hiring markets, especially in technology and artificial intelligence, equity compensation can be one of the few ways to attract top talent without burning excessive cash.
The mechanics: pre-money, post-money, and the option pool
The most common source of confusion is how dilution is calculated around a financing round. Investors typically negotiate based on a pre-money valuation, which is the company's value before new money comes in. Once the new investment is added, the company's post-money valuation reflects the new total. The investor's ownership percentage is generally determined by the size of the investment relative to the post-money valuation, though the exact outcome can also depend on whether the option pool is created or increased before or after the round.
That option pool detail matters because it can shift dilution toward founders. If investors require a larger employee option pool to be in place before they invest, the dilution from that pool is often borne by existing shareholders, not by the new investor alone. Founders sometimes focus on the headline valuation and miss the fact that the fully diluted cap table tells a different story. A term sheet that looks generous on valuation can still leave founders with less ownership than expected if the option pool is expanded aggressively. This is why legal and financial review matters before signing anything, especially for startups that are still refining governance and corporate structure. Founders navigating these issues often benefit from understanding related topics in employment, marketing, and innovation, where hiring and growth decisions intersect with equity planning.
What dilution does to control, not just ownership
Ownership and control are related but not identical. A founder may hold a minority economic stake and still retain significant control through board structure, voting rights, protective provisions, or dual-class shares, depending on the company's legal setup. Conversely, a founder can own a relatively large percentage and still lose strategic influence if investor rights are heavily negotiated. Early-stage founders sometimes focus too narrowly on equity percentage and overlook the governance terms that determine who can approve budgets, issue new shares, hire executives, or sell the company.
This is why dilution should be viewed alongside control rights. Investors may ask for board seats, veto rights on major transactions, or consent rights over future financings. Those terms can be reasonable in a venture-backed company, but they should be understood as part of the same bargain as dilution. A founder who gives up 20% of the company in one round may not just be reducing personal upside; they may also be changing how decisions are made. For a startup, that can be a healthy evolution if it brings discipline and expertise. It can also become a problem if founders give away too much too early without understanding the implications. Broader coverage of corporate structure and capital allocation in global and news can help place these decisions in a wider business context.
How much dilution is normal?
There is no universal "safe" dilution number, because acceptable dilution depends on the company's stage, capital needs, traction, and fundraising environment. A company with strong early traction may raise money on better terms than a pre-product startup. A capital-intensive business may need more money sooner and therefore accept more dilution. In general, though, founders should think in terms of ownership over the full life of the company, not just the current round. A single round may feel manageable, but several rounds plus option pool expansion can change the cap table dramatically.
The more useful question is whether the dilution is aligned with milestones. If a company gives up meaningful equity, it should ideally receive enough capital or strategic support to reach a materially better position for the next round or for profitability. If not, the company may be trading away ownership without buying enough time or progress. This is where discipline matters: founders should model multiple financing scenarios, not just the one they hope for. They should also understand how financing conditions can shift with broader market sentiment, rates, and investor appetite, all of which are reflected in economy coverage and sector-specific investment analysis.
Avoiding unnecessary dilution
Not all dilution is inevitable. Founders can reduce avoidable dilution by raising only the amount of capital they genuinely need, timing fundraises around stronger traction, and negotiating with a clear understanding of the company's valuation and cap table. They can also avoid over-allocating equity to early hires or advisors before those relationships are proven. A generous grant to someone who is still untested can become expensive if the company later needs to hire at scale.
Another common mistake is raising too early on weak terms because the company feels pressure to "get a round done." That can lead to a low valuation, a large investor stake, and a more restrictive financing structure than necessary. It is often better to spend more time building evidence of demand, retention, or revenue before taking outside capital. That said, waiting too long can also be costly if the company runs out of runway or misses a market window. The right answer is rarely "never dilute"; it is usually "dilute deliberately." For founders in fast-moving sectors such as crypto or sustainable, where market cycles and regulation can move quickly, deliberate timing is especially important.
The employee option pool is part of the dilution story
Many founders think of the option pool as a hiring tool, but it is also a financing tool because it affects how much ownership is left for everyone else. Investors often want enough unallocated equity in the company to support future hiring without immediately returning to the market for more capital. That makes practical sense, but it also means founders should understand whether the pool is sized for a realistic hiring plan or padded as a negotiating cushion. A pool that is too small creates future friction; one that is too large can unnecessarily dilute founders and early shareholders.
The best approach is usually to tie the pool to a credible hiring roadmap. If the company expects to add a technical lead, a sales head, and a few critical operators over the next 12 to 18 months, the pool should reflect that plan rather than a vague desire to "have room." Founders should also think about refreshes, vesting schedules, and whether grants are being used to reward actual value creation. Equity is most effective when it is linked to retention and performance, not handed out as a substitute for strategic thinking. Companies building in technology and artificial intelligence often rely heavily on this mechanism because competition for talent is intense and cash compensation alone may not be enough.
Practical questions founders should ask before signing
Before agreeing to a financing round or equity grant, founders should ask a few basic but critical questions: How much of the company will I own immediately after this transaction? How much will I own if the option pool is increased? What happens in the next round if the company raises again at a similar or lower valuation? What governance rights are attached to the new shares? And what milestones does this capital actually buy?
Those questions are not just legal formalities. They are the difference between a founder who understands the long game and one who is surprised by the cap table two years later. Founders should also pressure-test the downside case, not just the optimistic one. If growth slows, if fundraising conditions tighten, or if the company needs more capital than expected, dilution can accelerate quickly. In that sense, managing dilution is part finance, part strategy, and part risk management. It is closely connected to the same judgment calls that shape founders, business, and investment decisions.
Why dilution is not always a bad outcome
It is easy to frame dilution as something founders should avoid, but that is too simplistic. Some of the most successful companies in the world were built through repeated dilution because the value created by outside capital, talent, and market expansion was enormous. A smaller percentage of a very large company can be far better than a large percentage of a company that never scales. The key is whether the dilution is bought with progress.
That is why founders should think less about protecting a fixed percentage and more about protecting the quality of each trade. If capital helps the company reach product-market fit, if an option pool helps attract the right team, and if investor support helps unlock a larger opportunity, dilution can be a rational and even desirable part of the journey. The danger is not dilution itself; it is dilution without a clear purpose, a realistic model, or a full understanding of the consequences. For early-stage startups, that distinction is often what separates a painful cap table from a useful one.