Founder Equity Dilution Explained for Early-Stage Startups

Last updated by Editorial team at business-fact.com on Thursday 12 November 2026
Article Image for Founder Equity Dilution Explained for Early-Stage Startups

Founder Equity Dilution Explained for Early-Stage Startups

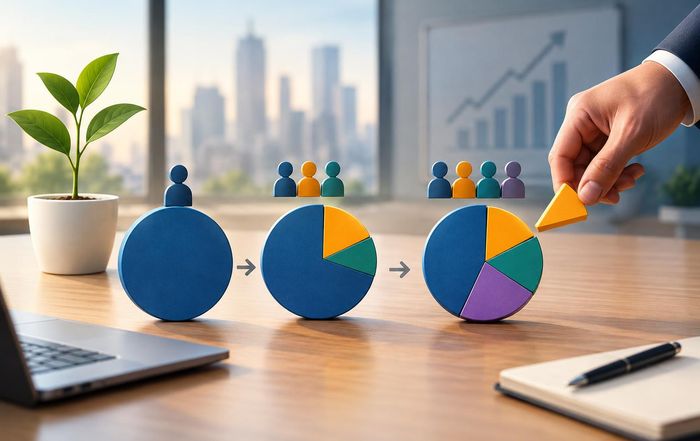
For early-stage startups, dilution is not a side issue; it is one of the central mechanics of building a company. Every new financing round, option grant, advisor allocation, or strategic hire can change how much of the business founders ultimately own and control. That does not automatically mean something has gone wrong. In many cases, dilution is the cost of turning an idea into a fundable, scalable company. The real question is whether founders understand what they are giving up, why they are giving it up, and how those decisions affect both incentives and long-term outcomes.

This matters especially in the earliest stages, when ownership percentages can look deceptively large and the consequences of each decision are easy to underestimate. A founder who owns 100% on day one may still end up with a minority stake after a seed round, an employee option pool refresh, and a few subsequent financings. That outcome can still be perfectly rational if the company is growing quickly and the value created is far greater than the ownership percentage surrendered. The challenge is to distinguish productive dilution from avoidable dilution, and to make those choices with a realistic view of fundraising, hiring, and control. For more ace context on startup strategy and capital formation, it can help to compare these trade-offs with key knowledge in founders, investment, and business.

What dilution actually means

Dilution occurs when a founder's percentage ownership falls because the company issues new shares or equity-linked securities to someone else. The founder may still own the same number of shares, but those shares represent a smaller slice of the company after the new issuance. In startup finance, that usually happens when the company raises capital from outside investors, creates or expands an employee stock option pool, or issues equity as part of a strategic transaction. The dilution is mathematical, but its business effect is strategic: ownership becomes more distributed, and the balance of incentives changes.

It is important to separate percentage ownership from economic value. A founder can be diluted from 80% to 40% and still become much wealthier if the company's valuation rises substantially. That is why dilution should not be judged in isolation. The relevant question is whether the capital or talent gained in exchange is likely to increase the company's total value enough to justify the reduced ownership. This is one reason early-stage founders spend so much time on cap tables, term sheets, and option pool sizing; small changes at the beginning can compound over time. For readers following the broader financing environment, the relationship between startup ownership and capital markets is often shaped by conditions in stock markets, economy, and banking.

Why early-stage founders get diluted so quickly

Early-stage companies usually have little revenue, limited operating history, and high execution risk. Because of that, outside capital tends to arrive in exchange for meaningful ownership. Investors are not just funding a product; they are pricing in the uncertainty that the company may fail, pivot, or require more capital than initially expected. Founders often accept dilution because without outside money they may not be able to hire, build, or market fast enough to compete. In that sense, dilution is often the bridge between a promising concept and a viable company.

Employee equity also creates dilution, and it is often underestimated by first-time founders. A startup that wants to hire experienced engineers, product leaders, or commercial talent may need a meaningful option pool to compete with larger employers. That pool is not "free" equity; it is usually carved out of the same total ownership base that founders and investors share. In practice, this means founders may be diluted even before a major financing round closes. For companies operating in competitive hiring markets, especially in technology and artificial intelligence, equity compensation can be one of the few ways to attract top talent without burning excessive cash.

The mechanics: pre-money, post-money, and the option pool

The most common source of confusion is how dilution is calculated around a financing round. Investors typically negotiate based on a pre-money valuation, which is the company's value before new money comes in. Once the new investment is added, the company's post-money valuation reflects the new total. The investor's ownership percentage is generally determined by the size of the investment relative to the post-money valuation, though the exact outcome can also depend on whether the option pool is created or increased before or after the round.

That option pool detail matters because it can shift dilution toward founders. If investors require a larger employee option pool to be in place before they invest, the dilution from that pool is often borne by existing shareholders, not by the new investor alone. Founders sometimes focus on the headline valuation and miss the fact that the fully diluted cap table tells a different story. A term sheet that looks generous on valuation can still leave founders with less ownership than expected if the option pool is expanded aggressively. This is why legal and financial review matters before signing anything, especially for startups that are still refining governance and corporate structure. Founders navigating these issues often benefit from understanding related topics in employment, marketing, and innovation, where hiring and growth decisions intersect with equity planning.

What dilution does to control, not just ownership

Ownership and control are related but not identical. A founder may hold a minority economic stake and still retain significant control through board structure, voting rights, protective provisions, or dual-class shares, depending on the company's legal setup. Conversely, a founder can own a relatively large percentage and still lose strategic influence if investor rights are heavily negotiated. Early-stage founders sometimes focus too narrowly on equity percentage and overlook the governance terms that determine who can approve budgets, issue new shares, hire executives, or sell the company.

This is why dilution should be viewed alongside control rights. Investors may ask for board seats, veto rights on major transactions, or consent rights over future financings. Those terms can be reasonable in a venture-backed company, but they should be understood as part of the same bargain as dilution. A founder who gives up 20% of the company in one round may not just be reducing personal upside; they may also be changing how decisions are made. For a startup, that can be a healthy evolution if it brings discipline and expertise. It can also become a problem if founders give away too much too early without understanding the implications. Broader coverage of corporate structure and capital allocation in global and news can help place these decisions in a wider business context.

How much dilution is normal?

There is no universal "safe" dilution number, because acceptable dilution depends on the company's stage, capital needs, traction, and fundraising environment. A company with strong early traction may raise money on better terms than a pre-product startup. A capital-intensive business may need more money sooner and therefore accept more dilution. In general, though, founders should think in terms of ownership over the full life of the company, not just the current round. A single round may feel manageable, but several rounds plus option pool expansion can change the cap table dramatically.

The more useful question is whether the dilution is aligned with milestones. If a company gives up meaningful equity, it should ideally receive enough capital or strategic support to reach a materially better position for the next round or for profitability. If not, the company may be trading away ownership without buying enough time or progress. This is where discipline matters: founders should model multiple financing scenarios, not just the one they hope for. They should also understand how financing conditions can shift with broader market sentiment, rates, and investor appetite, all of which are reflected in economy coverage and sector-specific investment analysis.

Avoiding unnecessary dilution

Not all dilution is inevitable. Founders can reduce avoidable dilution by raising only the amount of capital they genuinely need, timing fundraises around stronger traction, and negotiating with a clear understanding of the company's valuation and cap table. They can also avoid over-allocating equity to early hires or advisors before those relationships are proven. A generous grant to someone who is still untested can become expensive if the company later needs to hire at scale.

Another common mistake is raising too early on weak terms because the company feels pressure to "get a round done." That can lead to a low valuation, a large investor stake, and a more restrictive financing structure than necessary. It is often better to spend more time building evidence of demand, retention, or revenue before taking outside capital. That said, waiting too long can also be costly if the company runs out of runway or misses a market window. The right answer is rarely "never dilute"; it is usually "dilute deliberately." For founders in fast-moving sectors such as crypto or sustainable, where market cycles and regulation can move quickly, deliberate timing is especially important.

The employee option pool is part of the dilution story

Many founders think of the option pool as a hiring tool, but it is also a financing tool because it affects how much ownership is left for everyone else. Investors often want enough unallocated equity in the company to support future hiring without immediately returning to the market for more capital. That makes practical sense, but it also means founders should understand whether the pool is sized for a realistic hiring plan or padded as a negotiating cushion. A pool that is too small creates future friction; one that is too large can unnecessarily dilute founders and early shareholders.

The best approach is usually to tie the pool to a credible hiring roadmap. If the company expects to add a technical lead, a sales head, and a few critical operators over the next 12 to 18 months, the pool should reflect that plan rather than a vague desire to "have room." Founders should also think about refreshes, vesting schedules, and whether grants are being used to reward actual value creation. Equity is most effective when it is linked to retention and performance, not handed out as a substitute for strategic thinking. Companies building in technology and artificial intelligence often rely heavily on this mechanism because competition for talent is intense and cash compensation alone may not be enough.

Practical questions founders should ask before signing

Before agreeing to a financing round or equity grant, founders should ask a few basic but critical questions: How much of the company will I own immediately after this transaction? How much will I own if the option pool is increased? What happens in the next round if the company raises again at a similar or lower valuation? What governance rights are attached to the new shares? And what milestones does this capital actually buy?

Those questions are not just legal formalities. They are the difference between a founder who understands the long game and one who is surprised by the cap table two years later. Founders should also pressure-test the downside case, not just the optimistic one. If growth slows, if fundraising conditions tighten, or if the company needs more capital than expected, dilution can accelerate quickly. In that sense, managing dilution is part finance, part strategy, and part risk management. It is closely connected to the same judgment calls that shape founders, business, and investment decisions.

Why dilution is not always a bad outcome

It is easy to frame dilution as something founders should avoid, but that is too simplistic. Some of the most successful companies in the world were built through repeated dilution because the value created by outside capital, talent, and market expansion was enormous. A smaller percentage of a very large company can be far better than a large percentage of a company that never scales. The key is whether the dilution is bought with progress.

That is why founders should think less about protecting a fixed percentage and more about protecting the quality of each trade. If capital helps the company reach product-market fit, if an option pool helps attract the right team, and if investor support helps unlock a larger opportunity, dilution can be a rational and even desirable part of the journey. The danger is not dilution itself; it is dilution without a clear purpose, a realistic model, or a full understanding of the consequences. For early-stage startups, that distinction is often what separates a painful cap table from a useful one.
What Earnings Revisions Signal About Stock Market Direction

Last updated by Editorial team at business-fact.com on Wednesday 11 November 2026
Article Image for What Earnings Revisions Signal About Stock Market Direction

What Earnings Revisions Signal About Stock Market Direction

Earnings revisions are one of the clearest windows into how corporate America is being re-priced by analysts, executives, and investors. When estimates for future profits start moving higher across a broad group of companies, markets often treat that as a sign that business conditions are improving faster than expected. When revisions turn negative, the opposite message tends to dominate: margins may be under pressure, demand may be softening, or financing conditions may be tightening. That is why earnings revisions matter so much for anyone trying to understand stock-market trends, not just quarterly headlines.

The signal is useful because it reflects expectations before they show up in reported results. Markets are forward-looking, and share prices usually respond less to what a company earned last quarter than to what investors think it will earn over the next several quarters. That makes revisions a practical gauge of momentum, especially when they are happening across sectors rather than in just one isolated industry. For readers following investment decisions, the key question is not whether companies beat or miss by a few cents, but whether the underlying estimate trend is broadening or narrowing.

Why revisions matter more than the headline earnings number

A company can report strong quarterly earnings and still see its stock fall if guidance weakens or analysts trim forecasts for the rest of the year. The market is constantly discounting future cash flows, so the direction of estimates often matters more than the latest reported profit. This is especially true in periods when macro conditions are changing quickly, such as shifts in interest rates, consumer spending, or commodity prices. Analysts at major firms adjust their models as new information arrives, and those changes can reveal where the market sees hidden strength or emerging stress.

That is also why revisions can provide a broader reading than a single earnings season. A few large companies can distort the impression created by headline results, but a wide pattern of upward or downward estimate changes tends to be more informative. Investors often watch revision breadth, meaning whether more companies are seeing estimates raised than lowered. When breadth improves across industries such as technology, banking, and consumer sectors, it usually suggests that profit expectations are becoming more durable. When breadth deteriorates, especially across cyclical sectors, it can be an early warning that the market is becoming less comfortable with growth.

The mechanics behind an earnings revision cycle

Revisions usually follow a familiar sequence. Analysts start with assumptions about revenue growth, pricing power, costs, margins, and capital spending. As companies report results, issue guidance, or face changes in the macro backdrop, those assumptions are updated. If input costs rise, demand slows, or financing becomes more expensive, estimates often come down. If sales trends improve, costs stabilize, or management teams raise outlooks, estimates can move higher. The stock market then reacts not only to the revisions themselves, but also to whether they are happening earlier or later than expected.

This process matters because revisions can become self-reinforcing. When estimates rise, investors often become more willing to pay higher valuations, which can support share prices and reinforce confidence. Conversely, when estimates are cut repeatedly, valuations can compress even before profits visibly weaken. That dynamic is one reason earnings revisions are closely followed by portfolio managers and strategists at firms such as S&P Global, FactSet, and LSEG, whose data is widely used to track estimate trends. It is also why revisions are often discussed alongside economy indicators like growth, inflation, and labor-market data, rather than in isolation.

What upward revisions usually tell investors

Broad upward revisions generally suggest that corporate profits are tracking better than the market had anticipated. That can happen for several reasons: demand may be stronger, pricing may be holding up, cost pressures may be easing, or companies may be managing expenses more effectively. In some cases, the improvement is concentrated in a few sectors with unusual momentum, such as artificial intelligence infrastructure, cloud software, or industrial automation. In other cases, it reflects a wider improvement in the earnings environment, which is more powerful for stock-market direction because it supports multiple parts of the index rather than a narrow leadership group.

Upward revisions are especially meaningful when they come from sectors that tend to lead the cycle. Financials, industrials, semiconductors, and consumer discretionary companies often give clues about whether growth is broadening. If these groups begin to see estimate upgrades at the same time, investors may interpret that as confirmation that the economic backdrop is improving. That does not guarantee a market rally, but it often supports a healthier risk appetite. When combined with stable credit conditions and a cooperative interest-rate environment, rising revisions can be one of the strongest fundamental arguments for equity strength.

What downward revisions often warn about

Downward revisions do not always mean a market decline is imminent, but they often signal that expectations have become too optimistic. If analysts are cutting forecasts across a wide range of companies, it can indicate that margins are being squeezed or that customers are becoming more cautious. This is common when rates are high, borrowing is expensive, wage growth is sticky, or global demand is uneven. Sometimes the pressure begins in one area and spreads. For example, weaker industrial orders can eventually feed into logistics, staffing, and capital goods. A slowdown in consumer demand can later affect advertising, e-commerce, and payments businesses.

The most important warning sign is not a single cut but repeated cuts across several reporting cycles. Markets can absorb isolated disappointments, especially if expectations were already conservative. What they struggle with is a persistent pattern of negative surprises and lower forward guidance. That pattern often shows up first in employment-sensitive sectors or in companies exposed to discretionary spending. It can also appear when credit conditions tighten and borrowing costs rise, which is why revisions often move in step with developments in banking and lending markets. In those periods, equity investors tend to become more selective, rewarding companies with strong balance sheets and penalizing those that depend heavily on easy financing.

How revisions interact with valuation and market leadership

Earnings revisions do not operate in a vacuum. They matter most when paired with valuation. If estimates are rising but stocks are already priced for perfection, the upside may be limited. If estimates are falling but valuations are still expensive, the market can become vulnerable to sharp corrections. That is why professional investors often compare revision trends with price-to-earnings multiples, free cash flow, and return on capital. A stock or index can look cheap for a reason, and a strong revision trend can help explain whether that cheapness is temporary or justified.

Revision trends also help explain market leadership. In many cycles, a small number of sectors carry the index higher because their earnings outlook is improving faster than the rest of the market. That has been especially visible in periods when large technology and artificial intelligence-related firms have driven a disproportionate share of index earnings growth. But leadership can rotate. If revisions improve in innovation, artificial intelligence, or founders-led growth businesses while other areas lag, the market may still rise even if the average company is not seeing the same benefit. The reverse is also true: when leadership narrows too much, the market can become fragile even if headline indexes look strong.

Why revisions can be a better signal than sentiment alone

Investor sentiment can swing quickly on headlines, politics, or macro fears, but revisions are grounded in actual model changes and company commentary. That makes them a more disciplined indicator than mood alone. A market can feel pessimistic while estimates are quietly improving, or it can feel euphoric while estimates are already rolling over. The difference matters because prices tend to follow fundamentals over time, even if sentiment dominates for stretches. Analysts at institutions such as the Federal Reserve, the International Monetary Fund, and the OECD routinely emphasize that financial conditions, growth expectations, and corporate profitability interact in complex ways; revisions sit right at that intersection.

Still, revisions are not perfect. They can lag turning points, and analysts sometimes move too slowly when conditions change abruptly. They can also be influenced by management guidance that is intentionally cautious or strategically optimistic. That is why investors should treat them as one tool among several, alongside margins, credit spreads, macro data, and price action. A revision trend is most useful when it confirms what other indicators are already suggesting. It is less useful when it stands alone without support from sales trends, cash flow, or broader economic data.

Reading revisions in a global context

Although U.S. earnings estimates receive the most attention, revision trends matter in other major markets too. In Europe, where industrials, exporters, and banks can play an outsized role, revisions often reflect global trade demand and currency moves. In Asia, technology supply chains, semiconductors, and manufacturing cycles can shape the direction of estimates very quickly. In commodity-linked markets, revisions may be driven by energy prices, metals demand, or shipping costs. That is why global investors often track revisions across regions rather than assuming one market's pattern will hold everywhere.

For multinational companies, revisions can also reveal where growth is coming from geographically. A company may face pressure in one region but offset it with strength elsewhere. That matters for portfolio construction because the same stock can be sensitive to several different economic stories at once. Readers who follow global markets or news coverage will often notice that estimate changes cluster around the same themes: rates, demand, margins, and policy. The market's direction usually depends on whether those themes are improving or worsening in enough places to shift the aggregate earnings picture.

What investors should watch next?

The most useful way to interpret earnings revisions is to look for persistence. One quarter of upgrades can be noise. A multi-quarter pattern of rising estimates, especially when it spreads across sectors, is more convincing. Investors should also watch whether revisions are being driven by revenue growth or by cost cuts. Revenue-led upgrades tend to be healthier because they usually point to stronger demand. Cost-led upgrades can help profits in the short run, but they are less durable if the top line remains weak. In the same way, revisions that are concentrated in a handful of mega-cap names may not say much about the broader market.

For practical purposes, the question is whether estimate trends are improving enough to support current valuations. If the answer is yes, stocks often have a stronger foundation. If the answer is no, the market may be relying too heavily on optimism. That is why earnings revisions remain one of the most closely watched signals for equity direction: they translate scattered company-level information into a forward-looking picture of corporate health. For anyone trying to make sense of business, investment, and stock markets at the same time, they offer a disciplined way to separate temporary noise from a genuine change in trend.

How to Assess Business Expansion Risks Before Investing

Last updated by Editorial team at business-fact.com on Tuesday 10 November 2026
Article Image for How to Assess Business Expansion Risks Before Investing

How to Assess Business Expansion Risks Before Investing

Business expansion can look attractive on paper: higher revenues, a larger customer base, better margins from scale, and a stronger competitive position. But expansion also concentrates risk. New locations, new products, new markets, new hires, and heavier debt can all turn a promising growth story into a fragile one if the underlying assumptions are wrong. For investors, the central task is not simply to decide whether a company is growing, but whether that growth is durable, financeable, and resilient under stress.

A useful way to approach the question is to treat expansion as a sequence of bets rather than a single headline event. Is the company opening more stores, entering a new geography, building a factory, acquiring a rival, or investing in software and automation? Each path carries a different risk profile, and each should be tested against the same basic questions: how much capital is required, how long until returns appear, what can go wrong operationally, and how quickly can management adapt if demand disappoints. Those questions matter across sectors, whether the business sits in business, investment, economy, or global markets.

Start with the expansion thesis, not the excitement

Before looking at the numbers, investors should understand why the company believes expansion is the right move. A credible thesis usually rests on one of a few foundations: proven demand that exceeds current capacity, a market opportunity that is still underpenetrated, a cost advantage that becomes stronger at scale, or a strategic need to defend share against competitors. If management cannot explain which of those forces is doing the heavy lifting, the expansion may be more ambition than strategy.

This is where public filings, earnings calls, and management commentary become useful, but they should be read critically. Companies often present expansion as an obvious next step, especially when investors reward growth stories. The better question is whether the expansion is a response to a real bottleneck or merely a way to keep reported growth rates high. A business that is already stretched on working capital, dependent on a narrow product line, or facing weakening core demand may be using expansion to mask weakness rather than solve it. For context on how growth narratives can differ by sector, it can help to compare with broader trends in stock markets, technology, and innovation.

The best evidence of a sound thesis is not a polished slide deck but a pattern: a company has demonstrated repeatable unit economics in one market, the market is large enough to support replication, and the organization has shown it can operate at a larger scale without breaking quality, service, or financial discipline. If those ingredients are missing, the expansion case is weaker than it may first appear.

Test the economics at the unit level

Expansion risk becomes much easier to judge when the analysis shifts from company-wide revenue growth to unit economics. Investors should ask how much incremental profit each new store, plant, customer, or region is likely to generate after direct costs, overhead allocation, and the capital required to support it. That means looking beyond top-line growth and into contribution margins, payback periods, customer acquisition costs, and return on invested capital.

A business can grow quickly and still destroy value if each new unit requires too much spending to get off the ground. Retailers, hospitality groups, logistics firms, and subscription businesses often expose this issue clearly. A new location may generate sales, but if it takes too long to reach break-even, or if occupancy, labor, and logistics costs rise faster than expected, the expansion can dilute returns for years. The same logic applies to digital businesses that spend heavily on marketing to acquire customers but fail to retain them long enough to recover those costs.

Investors should also separate gross margin from true economic margin. Expansion frequently changes the cost mix: central overhead rises, local labor costs vary, shipping distances increase, and management attention gets stretched. If the company's reported margin profile depends on assumptions that only hold in the original market, expansion may compress profitability even when revenue rises. This is why analysts often compare the company's claims against broader data from institutions like the U.S. Securities and Exchange Commission, the Federal Reserve, and the International Monetary Fund when assessing financing conditions and macro sensitivity.

Check whether the balance sheet can absorb the strain

Even a strategically sensible expansion can become risky if the company is financially overextended. The balance sheet should be able to support the project without forcing the business into emergency financing, covenant pressure, or operational cuts elsewhere. Investors should look closely at debt levels, maturity schedules, interest coverage, liquidity, and the company's ability to fund expansion from operating cash flow rather than continuous external capital.

This matters because expansion often creates a timing mismatch. Costs arrive first, while benefits may arrive slowly and unevenly. If the company is borrowing to fund that gap, rising rates or tighter credit conditions can quickly change the economics. That is especially relevant in sectors sensitive to financing costs, including real estate, industrials, consumer services, and capital-intensive manufacturing. Broader credit conditions and banking behavior can be tracked through sources such as the Bank for International Settlements, the World Bank, and the Bank of England, all of which help frame how expensive or scarce capital may become.

Working capital deserves equal attention. A company may report rising sales but still face cash strain if inventories build too quickly, receivables stretch out, or supplier payments must be made before customers pay. Expansion can magnify those pressures. The more geographically dispersed or operationally complex the business becomes, the more cash it needs simply to keep the system moving. For investors, a strong income statement is not enough; the cash conversion cycle often tells the more honest story.

Measure execution risk, not just market opportunity

Many expansion plans fail not because the market is bad, but because execution is harder than management expected. New markets bring regulatory differences, customer behavior differences, hiring challenges, logistics issues, and unfamiliar competitive dynamics. A company that succeeds in one city or country may discover that its pricing, branding, supply chain, or service model does not translate cleanly elsewhere.

This is where operational detail matters. Investors should look for evidence that management understands local conditions, has realistic launch timelines, and has already solved the practical problems of scaling. If the expansion depends on hiring specialized talent, integrating new software systems, training frontline staff, or coordinating suppliers across borders, the execution burden is substantial. Businesses expanding in employment-sensitive sectors often underestimate how difficult it is to recruit and retain the right people at scale, especially when labor markets are tight.

A useful stress test is to ask what would happen if the rollout took twice as long as planned. Would the company still be financially stable? Would it still be able to serve existing customers well? Would management have to cut back on marketing, maintenance, or product development to keep the expansion alive? If the answer is no, then the expansion may be more fragile than the company admits. In many cases, the biggest danger is not failure in one dramatic moment, but a slow erosion of service quality and discipline as the organization stretches itself too thin.

Watch for overconfidence in management forecasts

Expansion plans are often built on optimistic assumptions, and optimism is not the same as fraud. Still, investors should be cautious when management guidance assumes smooth demand, rapid adoption, stable costs, and minimal disruption. The more ambitious the expansion, the more important it is to compare management's assumptions with historical performance and external benchmarks.

Good management teams usually discuss risks openly. They explain where they are uncertain, what conditions must hold for the plan to work, and how they will respond if results come in below expectations. Less disciplined teams tend to present expansion as a near-certainty. That is a warning sign. It can indicate weak internal challenge, incentive pressure to maintain growth narratives, or an unwillingness to confront the possibility of slower returns.

This is particularly relevant in sectors driven by hype cycles, including parts of artificial intelligence, crypto, and high-growth tech. In those areas, expansion can be justified by a large addressable market while the near-term economics remain unproven. Investors should distinguish between market potential and business quality. A large market does not automatically make a company's expansion wise, especially if customer retention, monetization, or regulatory clarity are still uncertain. When a company is expanding into a fast-changing field, the quality of its news flow and its ability to adapt matter as much as the initial strategy.

Examine the competitive response

Expansion rarely happens in a vacuum. Competitors notice, and they may respond with price cuts, better service, faster delivery, or heavier marketing. A company that is entering a new region or category may discover that incumbents defend their territory aggressively. Investors should ask whether the company has a genuine moat or whether it is simply assuming that scale alone will create one.

Competitive dynamics matter differently depending on the business model. In consumer-facing industries, brand strength and distribution can help. In industrial and B2B markets, switching costs, contracts, and technical expertise may matter more. In banking and financial services, regulation and trust can be decisive. In software, ecosystem lock-in and product integration may matter most. If the expansion plan depends on customers switching easily from established providers, the company may need to spend heavily to win share, which can compress returns for years.

It is also worth asking whether the expansion could trigger retaliation that hurts the core business. A company that pushes into a competitor's stronghold may invite aggressive pricing that spills back into its existing markets. That risk is often underappreciated because investors focus on the upside of new revenue rather than the downside of a broader competitive war. For a wider macro and sector context, it can help to keep an eye on banking conditions and regional market sentiment, both of which can influence how hard competitors are willing to fight.

Consider regulation, politics, and geography

Expansion across borders or into regulated industries adds another layer of uncertainty. Tax rules, labor laws, data protections, tariffs, licensing requirements, and environmental standards can all affect the economics of growth. A plan that looks straightforward in one jurisdiction may become much more expensive once compliance, reporting, and legal review are fully included.

This is especially important for companies expanding internationally. A business entering Europe, North America, or Asia may confront different consumer expectations and different regulatory frameworks, even when the product itself is similar. Currency movements can also change the result materially. Revenue earned in one currency may not translate into the same margin after conversion, hedging costs, and local inflation are considered. For investors, the key issue is not whether the company has a global ambition, but whether it has the operational and legal infrastructure to support that ambition responsibly.

Environmental and sustainability standards can also affect expansion choices. Projects that appear efficient in the short term may face higher costs if they run into carbon pricing, permitting delays, or supply chain scrutiny. That is why some investors now review sustainability risks alongside financial ones, particularly for energy-intensive, manufacturing, and logistics businesses. Useful background on these pressures can be found through the OECD, the United Nations, and the European Commission, all of which publish material on policy, trade, and regulatory direction.

Read the signals in the numbers

There is no single ratio that reveals expansion risk, but several indicators together can tell a strong story. Investors should examine revenue growth alongside operating margin trends, free cash flow, leverage, inventory turns, receivables quality, and capital expenditure intensity. If growth is rising while cash flow is weakening, the expansion may be consuming more capital than it creates. If margins are slipping as management adds complexity, the company may be growing in size but not in strength.

Comparative analysis helps. A company's expansion looks more credible when its economics are better than peers or when its return profile improves as it scales. If the opposite is true, the market may be rewarding a story that the numbers do not support. Investors should also pay attention to segment reporting, because a healthy core business can hide a weak expansion initiative. A company may report consolidated growth while a specific geography, product line, or acquisition drags on returns.

The most practical approach is to model downside scenarios. What happens if demand is 20% below plan, if costs rise faster than expected, or if the rollout takes longer to reach profitability? Companies that can still generate acceptable returns under conservative assumptions are far safer bets than those that only work under best-case conditions. For investors focused on resilience, that kind of analysis is often more revealing than the headline growth rate.

A disciplined investor's checklist

The final judgment should combine strategy, finances, operations, and external conditions. Expansion is most attractive when the company has proven demand, a clear competitive edge, manageable leverage, realistic timelines, and enough cash to absorb delays. It becomes much riskier when management is vague, the balance sheet is stretched, the unit economics are unproven, or the business is entering a market it does not truly understand.

That discipline is especially important for readers who follow entrepreneurship and growth investing because expansion stories can be compelling even when the evidence is thin. A company that is opening new markets or building a larger footprint may indeed be creating long-term value, but only if the risks are understood in advance. Investors who take the time to test the assumptions, rather than simply celebrate the ambition, are far better positioned to tell the difference between scalable growth and expensive overreach.

Why Employee Turnover Costs More Than Most Firms Expect

Last updated by Editorial team at business-fact.com on Monday 9 November 2026
Article Image for Why Employee Turnover Costs More Than Most Firms Expect

Why Employee Turnover Costs More Than Most Firms Expect

Employee turnover is often treated as a recruiting problem, but the real cost is usually a broader operating problem. When a worker leaves, the visible expense is the job ad, the recruiter fee, or the signing bonus for a replacement. The larger bill tends to arrive later, in the form of lost productivity, manager time, disrupted customer relationships, lower team morale, and the drag that comes from having new people learn the business while the work still has to get done. That is why turnover can be far more expensive than many firms assume, especially in roles where institutional knowledge, customer trust, or technical skill matters. For companies trying to control labor costs, the issue is closely tied to employment, business operations, and even innovation, because replacing people is never just a staffing event. It is a productivity event, a leadership event, and often a financial event with ripple effects that last well beyond the vacancy itself.

The direct costs are only the easiest to see

Most firms can identify the obvious expenses. There is the cost of advertising a role, screening applicants, interviewing candidates, and onboarding the new hire. If the company uses external recruiters, that fee can be substantial. If the role is specialized, the replacement may come with a salary premium, relocation support, or a signing incentive. These are real costs, but they are also the easiest ones to budget for, which is why they tend to dominate management discussions. What is often missed is that the direct replacement cost is only one layer of the total. Research from organizations such as the Society for Human Resource Management, the U.S. Bureau of Labor Statistics, and the OECD repeatedly shows that labor markets are dynamic and that turnover is common enough to be a structural business issue rather than an occasional inconvenience. The challenge for employers is that the most expensive effects are often indirect, and indirect costs are harder to measure, slower to appear, and easier to underestimate.

A vacant role also creates a temporary productivity gap. Work that was handled by one person does not disappear when that person resigns. It is redistributed to coworkers, managers, or contractors, often at a lower level of efficiency. That redistribution can slow projects, increase error rates, and create bottlenecks in functions that depend on coordination. In a sales team, the lost time may show up as delayed follow-ups or missed renewals. In a manufacturing or logistics environment, it may appear as scheduling friction or quality issues. In a finance, legal, or technology role, the cost can be even more pronounced because the departing employee may have held process knowledge that is not fully documented anywhere else. That is why turnover is not just a human resources metric; it is a stock markets issue for publicly traded firms, a profitability issue for private companies, and a resilience issue for organizations in highly competitive sectors.

The hidden bill shows up in lost output and slower execution

The largest cost of turnover is usually the period between departure and full replacement performance. New hires need time to reach the productivity level of the people they replace, and that ramp-up period can be longer than managers expect. Even experienced hires from outside the organization must learn systems, internal politics, customer preferences, compliance requirements, and the informal ways work actually gets done. That learning curve has a cost, and it often falls on the most experienced remaining employees, who must train, supervise, and absorb extra work while still meeting their own targets. This is one reason turnover can become self-reinforcing: the departure of one person increases pressure on the rest of the team, and that pressure can raise the odds that additional employees begin looking elsewhere.

The quality of output can also decline before a replacement is fully settled. Teams under strain are more likely to make avoidable mistakes, miss deadlines, or defer nonurgent work that later becomes urgent. In customer-facing roles, service quality may slip in ways that are not immediately visible in accounting statements. In technical roles, turnover can slow product development, delay releases, or weaken institutional memory around past design decisions. These effects are especially damaging in businesses where speed matters, such as technology, artificial intelligence, and fast-moving digital services. For companies in those sectors, turnover can quietly erode competitive position long before the finance team notices a larger payroll line.

Culture damage is expensive because it changes behavior

Turnover does not just remove labor; it changes the social environment in which the remaining employees work. When people see frequent departures, they often begin to question leadership stability, career prospects, and whether the organization is worth investing in emotionally. That shift can lower discretionary effort, reduce collaboration, and weaken the informal knowledge-sharing that makes teams efficient. Managers may spend more time reassuring staff, handling morale issues, or revisiting priorities that would otherwise have been settled. A company may believe it is paying only to replace one employee, but in practice it may also be paying for a broader decline in confidence.

This effect is often strongest when departures are concentrated in a single department or among a particular level of seniority. Losing one junior employee is disruptive; losing several experienced people can alter the culture of an entire unit. The problem is not only the number of people leaving but the pattern they create. High turnover can signal poor management, weak pay competitiveness, limited progression, or unrealistic workloads. Once that reputation takes hold, recruiting becomes harder and retention becomes even more expensive. Companies that are trying to improve retention often need to look beyond compensation alone and examine management quality, role design, flexibility, and the basic employee experience. For firms watching labor conditions closely, that is one reason global workforce trends matter even when the business itself is local.

Customer relationships often leave with the employee

In many businesses, employees are part of the product. That is especially true in advisory services, banking, consulting, sales, account management, and other relationship-heavy functions. When a trusted employee leaves, the company may lose not only their labor but also the confidence of the clients or counterparties who worked with them. The replacement may be competent, but trust usually takes time to transfer. In some cases, customers follow the departing employee to a competitor. In others, the relationship remains with the firm but weakens during the transition, reducing renewal rates, upsell opportunities, or referral flow.

This is one reason turnover can be especially costly in industries where reputation compounds over time. A customer who feels ignored during a staffing transition may not complain immediately, but the lost business can surface months later in lower retention or weaker contract renewal terms. The same is true in sectors where continuity matters, such as banking, wealth management, and specialized B2B services. For leadership teams, the lesson is that retention is not just about keeping headcount stable. It is about preserving continuity in the relationships that generate revenue. That is also why turnover analysis should sit alongside investment decisions: the cost is not merely an HR expense, but a drag on asset quality, client loyalty, and future earnings potential.

Why the estimate is usually too low

Many companies underestimate turnover because they count only the costs that pass through a budget line. They may include recruiter fees and onboarding, but not the value of lost output, the time managers spend in interviews, the overtime paid to cover gaps, or the quality losses that occur while a team is understaffed. They may also undercount the cost of turnover because some of it is distributed across departments. Finance absorbs the payroll premium, operations absorbs the productivity loss, sales absorbs the relationship risk, and senior leadership absorbs the strategic delay. If no single department owns the full problem, the business may never see the total cost in one place.

There is also a tendency to average turnover costs across all roles, which can hide how expensive specific departures are. Replacing a front-line worker is not the same as replacing a software engineer, a plant supervisor, or a revenue-producing account executive. Seniority, specialization, and customer exposure all change the economics. A single departure in a small firm can be more disruptive than several departures in a larger one because fewer people are available to absorb the work. That is especially true in founder-led businesses, where knowledge is concentrated and processes may not be deeply documented. For that reason, founders and management teams should be cautious about using broad industry averages as if they were precise internal benchmarks.

Retention is often cheaper than replacement, but only if it is targeted

The business case for retention is strongest when companies focus on the employees whose departure would be most damaging. Not every employee needs the same level of investment, and not every retention problem should be solved with higher pay. Some employees leave because of weak scheduling, poor manager behavior, a lack of development, or unclear progression. In those cases, the most effective intervention may be redesigning the job, improving supervision, or creating a more predictable career path. In other cases, pay is the central issue, and firms that fall behind the market eventually pay more in replacement costs than they would have spent on raises.

A targeted retention strategy works best when it is built on data rather than assumptions. Exit interviews, stay interviews, manager feedback, and turnover by team or tenure can reveal where losses are concentrated. Firms can then compare the cost of replacing employees with the cost of keeping them. That comparison often changes the conversation. A modest increase in compensation, better scheduling, or more flexible work design may look expensive in isolation, but it can be far cheaper than repeated recruiting, training, and lost output. In a tight labor market, retention is not a soft people initiative; it is a cost-control measure. It also intersects with marketing and employer brand, because the way a company treats employees increasingly shapes how it is perceived by candidates, customers, and business partners.

The wider economy makes turnover more expensive in some periods

The cost of turnover is not fixed. It rises and falls with labor market conditions, wage pressure, and the availability of qualified candidates. When unemployment is low or certain skills are scarce, replacement becomes slower and more expensive. When inflation is elevated, wage expectations can rise quickly, and employers may need to pay more to attract or retain talent. In some economies, changes in labor participation, immigration policy, or sector-specific demand can also make hiring harder. That is why turnover should be viewed in the context of the broader economy, not as a standalone HR statistic.

Public data from institutions such as the International Labour Organization, the World Bank, and national statistical agencies help explain why turnover pressure varies across markets. In some periods, workers have more options and more bargaining power, which increases the cost of replacement. In others, firms may find it easier to hire, but the hidden cost of turnover can still remain high if onboarding time is long or institutional knowledge is hard to replace. This is why companies that track turnover only when hiring becomes difficult are usually reacting too late. The better approach is to treat retention as an ongoing operating metric, not a temporary response to a difficult labor market.

What firms should measure instead of guessing

A useful turnover analysis goes beyond a simple annual percentage. Companies should measure turnover by role, tenure, manager, location, and performance band, then compare those patterns with productivity, customer satisfaction, overtime, and time-to-fill. They should also estimate the full replacement cycle, including the time until a new hire reaches expected output. In many cases, the real cost is not a single event but a sequence: departure, vacancy, temporary coverage, recruiting, onboarding, ramp-up, and then the recovery period before the team is back to normal. That sequence can take months.

Firms that want a clearer picture can also compare turnover costs with the cost of prevention. That means looking at manager training, compensation alignment, internal mobility, workload design, and benefits that reduce avoidable exits. The goal is not to eliminate all turnover, which is neither realistic nor always desirable, but to reduce the kind that destroys value. For readers following broader business trends, the issue connects naturally to employment, business, and innovation because organizations that retain knowledge, maintain continuity, and keep teams stable usually execute better than those that treat departures as routine admin.

The firms that understand this best tend to ask a different question. Instead of asking how much it costs to replace an employee, they ask how much value the business loses every time a capable person walks out the door. That is usually the more expensive number.

What Employment-to-Population Ratios Reveal About Jobs

Last updated by Editorial team at business-fact.com on Sunday 8 November 2026
Article Image for What Employment-to-Population Ratios Reveal About Jobs

What Employment-to-Population Ratios Reveal About Jobs

The employment-to-population ratio is one of the clearest ways to see how much of a country's working-age population is actually employed. Unlike the unemployment rate, which only counts people actively looking for work, this measure captures the share of the broader population that has a job. That makes it especially useful when labor markets are distorted by low participation, aging populations, discouragement, or large shifts in schooling, caregiving, migration, or retirement. For readers following labor-market trends, it can reveal whether job growth is truly broad-based or whether headline employment figures are masking a weaker reality. It also helps explain why two economies with similar unemployment rates can feel very different on the ground. For a broader view of how labor trends connect to the wider economy, see employment, economy, and global.

At its simplest, the ratio is a stock measure: employed people divided by the total population in a chosen age group, usually the working-age population. That makes it different from job creation counts, which measure change over time, and different again from the unemployment rate, which is a share of the labor force rather than the whole population. Because the denominator is larger, the employment-to-population ratio can fall even when unemployment appears stable, especially if more people stop looking for work. It can also rise without a dramatic drop in unemployment if more people enter the labor force and find jobs at the same time. In practice, the ratio is often a better summary of how much of a society's human capacity is being used. Official labor data from institutions such as the International Labour Organization, the OECD, the World Bank, and national statistical agencies are the main sources analysts use to track it.

Why the ratio can tell a different story from unemployment

The unemployment rate is widely reported because it is intuitive and moves quickly, but it has a built-in limitation: it excludes people who are not in the labor force. That includes students, retirees, caregivers, people with disabilities, early retirees, discouraged workers, and others who are neither employed nor actively seeking work. If a weak labor market pushes some job seekers to stop looking, the unemployment rate can improve even though the labor market has not truly strengthened. The employment-to-population ratio is less vulnerable to that distortion because it looks at how many people actually have jobs relative to the population base. In that sense, it often provides a more honest picture of labor-market inclusion.

This is why economists often read the ratio alongside labor-force participation, wages, and hours worked rather than in isolation. A country can have a low unemployment rate but still a weak employment-to-population ratio if many adults are outside the labor force. That pattern matters for tax revenues, consumer spending, household formation, and long-run growth. It also matters for sectors tracked by Business-Fact such as banking, investment, and stock markets, because labor-market breadth influences credit demand, consumption, corporate earnings, and expectations for central-bank policy. In other words, the ratio is not just a labor statistic; it is a useful proxy for how widely the gains from economic activity are being shared.

What moves the ratio up or down

Employment-to-population ratios rise when more people find work, but they can also move because of demographic change. A country with a growing share of older adults may see the ratio decline even if job opportunities are stable, simply because more people are retired. The same can happen when more young people stay in education longer, when migration patterns shift, or when caregiving responsibilities keep some adults out of paid employment. For this reason, analysts usually compare age-specific ratios rather than relying only on the overall figure. The ratio for prime-age workers, often ages 25 to 54, is especially useful because it strips out some of the noise from school enrollment and retirement.

Policy and economic cycles matter too. During recessions, the ratio often falls sharply as layoffs increase and new hiring slows. Recovery can be uneven: firms may rehire slowly, and some workers may remain detached from the labor market even after growth resumes. Structural factors also play a role, including childcare availability, disability support, health trends, immigration rules, and the level of automation in the economy. In countries with strong social safety nets, the ratio may be lower than in countries where more adults must work to maintain household income, but that does not automatically imply a weaker economy. Context matters. The right question is not whether the number is high or low in the abstract, but what it says about labor-market access, incentives, and the composition of the population. For related coverage of how new technologies and business models affect work, see technology, artificial intelligence, and innovation.

What it reveals in practice

The ratio is most useful when it is compared across time, age groups, and countries. In the United States, for example, the prime-age employment-to-population ratio has often been treated as a key signal because it is less affected by retirement trends than the overall measure. In Europe, comparisons can be shaped by differences in childcare, part-time work, and retirement systems. In some economies, a relatively modest unemployment rate can coexist with a lower employment-to-population ratio because a larger share of adults is not working at all. In others, the ratio can be higher even if unemployment is somewhat elevated, because more people are engaged in the labor market overall. That is one reason international organizations such as the OECD and Eurostat emphasize harmonized labor indicators.

For investors and business leaders, the ratio can be a clue to the depth of consumer demand. A rising employment-to-population ratio generally means more households have wages coming in, which can support retail spending, borrowing, and business expansion. A falling ratio can signal hidden slack even if headline unemployment looks acceptable. It may also suggest future pressure on public finances if fewer workers are supporting more dependents. These effects are not confined to one country. Across major markets, labor-force health affects everything from housing demand to credit quality to the speed at which firms can hire. That is why the ratio belongs in any serious discussion of jobs, not just in labor economics papers or government releases.

Where the measure can mislead

No single labor statistic is perfect, and the employment-to-population ratio has its own blind spots. It treats all employment as equal, whether the job is full-time or part-time, stable or precarious, well paid or low paid. A rise in the ratio may reflect more people taking lower-quality or shorter-hours jobs rather than a stronger labor market in a broader sense. It also does not show underemployment, multiple job holding, or whether workers are using their skills effectively. A country can post a healthy ratio while many workers remain stuck in insecure or low-productivity roles.

Another limitation is demographic composition. If a population is aging rapidly, the overall ratio can fall even when employment prospects for working-age adults are improving. That is why analysts often prefer age-adjusted comparisons or prime-age measures. There is also a timing issue: the ratio is usually published with a lag and can be revised as survey data are updated. In fast-changing labor markets, especially during shocks such as pandemics or financial crises, the ratio is valuable but not instant. It should be read with payroll data, vacancy data, wage growth, and participation rates. Official sources such as the U.S. Bureau of Labor Statistics, Statistics Canada, the UK Office for National Statistics, and Australia's ABS are useful for following those complementary measures.

The signals readers should watch

For anyone trying to judge whether jobs are truly improving, the most useful approach is to watch the employment-to-population ratio alongside a few companion indicators. A healthy labor market usually shows a rising or stable ratio, steady participation, and wage gains that are not being eroded by inflation. If the ratio is flat while unemployment falls, the labor market may be improving only because people are leaving the labor force. If the ratio rises but wages stagnate, the economy may be creating jobs without creating much bargaining power for workers. If the ratio declines in a period of growth, that can be a warning that the recovery is narrow or uneven.

That is why the measure has enduring value for journalists, policymakers, employers, and readers trying to understand what is really happening beneath the headline numbers. It does not replace the unemployment rate; it complements it. But in many situations it tells the more important story: not just how many people are looking for work, but how many people are actually connected to employment at all. For readers tracking labor-market conditions across sectors and countries, that distinction is often the difference between a misleading snapshot and a genuinely useful picture of jobs.

How Dividend Payout Ratios Affect Long-Term Stock Returns

Last updated by Editorial team at business-fact.com on Saturday 7 November 2026
Article Image for How Dividend Payout Ratios Affect Long-Term Stock Returns

How Dividend Payout Ratios Affect Long-Term Stock Returns

Dividend payout ratios sit at the center of a long-running debate in investing: how much of a company's earnings should be returned to shareholders, and how much should be kept for growth? The answer is rarely simple. A high payout ratio can signal mature cash generation, discipline, and shareholder friendliness, but it can also suggest limited reinvestment capacity or an unsustainable dividend if earnings weaken. A low payout ratio may leave more room for expansion, acquisitions, or debt reduction, yet it can also reflect a company that is still building its business rather than distributing cash. For investors, the key question is not whether payout ratios are "good" or "bad," but how they influence the mix of income, growth, valuation, and risk that ultimately drives long-term returns.

That distinction matters because dividend policy is only one part of the return equation. Over long periods, stock returns come from a combination of dividends, earnings growth, and changes in valuation. A company that pays out a large share of earnings may deliver attractive current income but slower compounding if it cannot reinvest enough to grow. A company that retains most of its earnings may produce better capital appreciation if those retained profits are deployed at high returns on capital. In practice, the best outcome depends on the business model, industry structure, balance sheet strength, and the price an investor pays for the shares. For more context on the corporate and market side of that equation, it helps to look alongside stock market trends, investment strategy, and the wider business environment.

What the payout ratio actually tells investors

The dividend payout ratio is usually defined as dividends paid divided by net income, though some analysts prefer free cash flow because accounting earnings can be distorted by non-cash items. A payout ratio of 40%, for example, means the company distributes 40 cents of every dollar of earnings as dividends and retains the rest. That retained portion can fund capital spending, research, hiring, acquisitions, debt repayment, or share repurchases. In theory, a company should retain capital only when it can earn more than shareholders could earn elsewhere after adjusting for risk. In practice, management teams often balance reinvestment needs, debt covenants, investor expectations, and the desire to maintain a stable dividend through the cycle.

For that reason, the ratio is best read as a clue about capital allocation rather than as a standalone quality metric. A utility, telecom, or mature consumer staples company may reasonably have a high payout ratio because its growth opportunities are limited and its cash flows are relatively steady. A fast-growing software, biotech, or industrial company may have a low or even zero payout ratio because it can create more value by reinvesting earnings. Investors who want to compare capital allocation across sectors can use related coverage such as economy, technology, and innovation to understand why payout norms vary so much by industry.

The ratio also matters because it can reveal fragility. A payout ratio that looks comfortable in a strong year can become dangerous if earnings are cyclical. If a company pays out most of its profits during a peak period and then earnings normalize, the dividend may have to be cut, which often hurts investor sentiment and can pressure the share price. That is why many long-term investors focus not just on the size of the dividend, but on the durability of the business and the consistency of cash generation. Reliable dividend analysis often requires looking at banking, employment, and broader global conditions, since macroeconomic shifts can quickly alter earnings quality and payout capacity.

Why payout ratios influence long-term returns

Dividend payout ratios affect long-term returns through three main channels: reinvestment, compounding, and valuation. First, retained earnings can be powerful when management allocates them well. If a company can reinvest at high incremental returns, every dollar not paid out may generate more than a dollar of future value. That is one reason many high-growth companies historically paid little or no dividend while they expanded. The opposite is also true: if a company cannot reinvest retained profits at attractive rates, keeping too much cash inside the business can destroy value through low-return projects, empire building, or inefficient acquisitions.

Second, dividends themselves can accelerate compounding when reinvested by shareholders. A company with a moderate payout ratio and steady earnings growth can produce strong total returns if dividends are consistently reinvested into additional shares. This effect is especially important over decades. Even when the share price moves sideways for long stretches, reinvested dividends can materially improve the investor's outcome. That is why dividend-focused strategies often emphasize total return rather than yield alone. A stock with a high yield is not automatically superior if the business is shrinking or if the market expects a dividend cut.

Third, payout ratios can influence how the market values a stock. Investors often assign different valuation multiples depending on whether a company is viewed as a growth compounder, a stable income generator, or a cyclical business with uncertain cash flows. A lower payout ratio can support a higher valuation if the market believes retained earnings will be reinvested at attractive rates. A higher payout ratio can also support valuation if investors prize stability and cash distribution, especially in uncertain markets. For readers who want to connect this to market pricing and sector behavior, investment and stock markets are useful lenses.

When a high payout ratio helps and when it hurts

A high payout ratio is often most attractive in mature businesses with stable demand, modest capital requirements, and limited need for heavy reinvestment. In those cases, returning cash to shareholders can be more efficient than retaining it. Investors in such companies are often seeking dependable income and lower volatility rather than rapid growth. Large, established firms in sectors like consumer staples, utilities, and some financials often fit this profile, although each company still needs to be judged on its own merits. From an income perspective, the appeal is straightforward: more cash is paid out now, and less is left to management discretion.

But a high payout ratio becomes problematic when it leaves too little cushion. If earnings are volatile, a high dividend commitment can force the company to borrow, sell assets, or cut the dividend during downturns. That is often where disappointment begins. A dividend cut can be especially damaging because it may signal that the company's prior distribution policy was too aggressive or that the underlying business has weakened. Investors should therefore pay attention to whether the payout ratio is based on earnings, cash flow, or adjusted earnings, and whether those figures are sustainable in a more normal environment. A company whose dividend consumes most of its free cash flow may have little room to absorb shocks.

There is also a valuation trap. Some stocks appear attractive because they offer a high yield and a high payout ratio, but the market may be pricing in a decline. In that case, the yield can be a warning sign rather than a bargain. Long-term investors need to distinguish between a genuinely cash-rich business and one whose dividend is large only because the share price has fallen. This is where a broader view of the company's fundamentals, sector cycle, and macro backdrop becomes essential. Publications focused on news and global developments often show how quickly sentiment can change when interest rates, commodity prices, or consumer demand shift.

Why lower payout ratios can outperform over time

Lower payout ratios often support stronger long-term growth when a company has profitable opportunities to reinvest. This is the classic compounding story: instead of distributing most earnings, the business keeps capital inside the firm and uses it to expand capacity, develop products, enter new markets, or improve efficiency. If the return on that reinvested capital exceeds the company's cost of capital, shareholders can benefit from faster earnings growth and rising intrinsic value. In such cases, a lower dividend today may be the price of a much larger future payoff.

This is especially relevant in sectors where competitive advantage depends on continuous investment. Technology companies, many industrial innovators, and some consumer brands often need to spend heavily on product development, infrastructure, or customer acquisition before those investments generate durable profits. In these cases, a high payout ratio could be a sign that management is prioritizing short-term income over long-term value creation. That does not mean dividends are unimportant; it means the business may be better served by retaining capital until growth opportunities mature. Readers tracking these dynamics may also find the publication's coverage of artificial intelligence and founders useful, since many fast-growing companies are still in the reinvestment phase.

Still, a low payout ratio is not automatically a positive. It only works when retained earnings are actually productive. A company can hoard cash, overinvest, or pursue acquisitions that dilute returns. In those cases, shareholders may be better off if more capital were returned. The crucial distinction is between retention that compounds value and retention that merely enlarges the balance sheet. Over long horizons, investors usually reward disciplined capital allocation more than they reward any fixed dividend policy.

The role of sector, cycle, and balance sheet

Dividend payout ratios cannot be judged outside their operating context. Sector economics matter because different industries require different levels of reinvestment. Banks, insurers, utilities, and mature consumer companies often have higher payout norms, while software, biotech, and many growth-oriented businesses tend to retain more earnings. Cyclicality matters too. A cyclical company may look generous at the top of the cycle and stretched at the bottom. Investors who ignore that pattern can overestimate the sustainability of the dividend and underestimate the risk of a cut.

Balance sheet strength is equally important. A company with moderate leverage and strong free cash flow can often support a higher payout ratio than a heavily indebted peer. Debt service absorbs cash that might otherwise go to dividends, and refinancing risk can become a serious issue when interest rates rise. That is one reason macro conditions and monetary policy matter so much to income investors. A dividend that looks safe in a low-rate environment may become less comfortable when borrowing costs increase or credit conditions tighten. For readers following those pressures, banking and economy coverage can provide useful context.

The payout ratio also interacts with share buybacks. Some companies return capital through a combination of dividends and repurchases, which means the headline payout ratio may understate the total amount of capital being returned. That can make comparisons tricky. A company with a moderate dividend but aggressive buybacks may be returning more cash overall than a company with a higher dividend alone. For that reason, long-term investors should examine total shareholder yield rather than focusing narrowly on the dividend. That broader lens often gives a better picture of how management is balancing income, reinvestment, and flexibility.

What long-term investors should watch instead of chasing yield

A useful dividend analysis starts with cash flow coverage, not yield alone. Investors should ask whether the dividend is covered by free cash flow, whether earnings are stable enough to support the payout through a downturn, and whether the company still has enough capital to invest for growth. They should also look at the direction of the payout ratio over time. A rising ratio can be a warning sign if dividends are growing faster than earnings. A falling ratio can be healthy if earnings are expanding faster than distributions, or it can simply reflect management becoming more conservative.

It is also worth asking what else the company could do with the money. If retained capital is likely to earn high returns, a lower payout ratio may be the more rational choice. If the business has limited growth prospects, a higher payout ratio may be appropriate. This is why dividend policy is ultimately a question of opportunity cost. Every dollar paid out is a dollar not invested in the business, and every dollar retained is a dollar not immediately available to shareholders. The best capital allocation decisions are those that maximize long-term per-share value, not just current distributions.

For investors building portfolios around income, the lesson is not to avoid dividends or to prefer one payout ratio across all stocks. It is to match the payout profile to the business quality, growth runway, and risk tolerance of the portfolio. A well-chosen mix of mature dividend payers and selective growth companies can produce a more resilient return stream than an undifferentiated hunt for the highest yield. That is especially true in a world where sector rotation, interest rates, and global growth trends can alter investor preferences quickly. The most durable long-term returns usually come from businesses that can both reward shareholders today and still create value tomorrow.

US Small Business Lending Trends and Credit Challenges

Last updated by Editorial team at business-fact.com on Friday 6 November 2026
Article Image for US Small Business Lending Trends and Credit Challenges

US Small Business Lending Trends and Credit Challenges

Small business credit in the United States has entered a more complicated phase. After years of unusually cheap money, lenders, borrowers, and policymakers are now operating in a higher-rate environment where cash flow matters more, underwriting is tighter, and the cost of waiting for financing can be significant. For many founders and owners, the central question is no longer simply whether credit is available, but which kind of credit is available, on what terms, and with what trade-offs attached. That shift is reshaping everything from short-term working capital decisions to long-planned expansion projects.

The broader backdrop matters. The Federal Reserve has kept policy restrictive relative to the ultra-low-rate period that followed the pandemic, and that has fed through to business borrowing costs. At the same time, smaller firms continue to face uneven access to credit depending on revenue volatility, collateral, personal guarantees, industry risk, and local banking conditions. Data from the Federal Reserve's Senior Loan Officer Opinion Survey has repeatedly shown tighter standards in recent periods, while the U.S. Small Business Administration continues to play an outsized role in supporting lending through guarantees and program structure. The result is not a simple credit crunch, but a more selective market in which strong borrowers can still borrow, while weaker or younger firms often encounter higher friction.

Why small business credit is harder to navigate now

The most important change in recent lending conditions is that "good enough" business performance is no longer good enough for many lenders. Banks and nonbank lenders alike are paying closer attention to debt service coverage, seasonal revenue swings, customer concentration, and the stability of deposits. That is especially relevant for firms in cyclical sectors such as retail, hospitality, construction, and transportation, where revenues can change quickly and fixed costs leave little room for error. In a lower-rate era, lenders could sometimes rely on asset values or anticipated growth to justify a loan. In the current environment, they are more likely to insist on evidence that cash flow can support repayment even if conditions worsen.

This is one reason the market has become more segmented. Larger established firms with clean financials may still obtain attractive terms from banks or credit unions, while newer businesses often turn to online lenders, merchant cash advance providers, invoice financing platforms, or SBA-backed loans. Those alternatives can be useful, but they usually come with either higher pricing, shorter repayment periods, or more restrictive advance structures. Readers following the broader business cycle may want to compare these patterns with developments in the economy and banking, because lending conditions are increasingly tied to the same forces that shape inflation, funding costs, and bank balance-sheet behavior.

The shift also reflects caution after a period of stress in parts of the banking system. Depositor sensitivity, balance-sheet management, and regulatory scrutiny have made many institutions more conservative about commercial lending. That does not mean banks have stopped lending to small businesses; rather, they have become more selective about borrower quality, loan size, and sector exposure. For business owners, that selectivity can feel like a sudden tightening, even when aggregate credit is still flowing.

The role of banks, fintech lenders, and SBA programs

Small business finance in the U.S. is no longer dominated by a single channel. Traditional banks still matter enormously, especially for relationship-based lending and deposit-linked customers, but they are now competing with fintech lenders that can move faster and underwrite differently. The trade-off is familiar: banks often offer lower rates and longer terms, while nonbank lenders may approve faster and accept borrowers that banks decline. For an owner trying to keep payroll on track or finance inventory ahead of a busy season, speed can outweigh price. For a borrower planning a multi-year expansion, rate and structure usually matter more than convenience.

The SBA remains central because its guarantee programs help bridge the gap between conservative bank underwriting and the financing needs of smaller firms. SBA-backed loans are not automatic approvals, and they still require documentation, credit review, and a viable business plan, but the guarantee can make lenders more willing to take on borrowers who might otherwise be excluded. That matters especially for startups, franchisees, and businesses with limited collateral. It also helps explain why the SBA remains one of the most important institutions in the small business credit ecosystem, even when private credit markets are active.

A useful way to think about the modern market is to compare it with the broader financial system. The Federal Deposit Insurance Corporation and the Office of the Comptroller of the Currency both influence how banks manage risk, capital, and supervision, while the Consumer Financial Protection Bureau has an indirect but relevant role in transparency and fair lending oversight. For business owners, those institutions shape the lending environment in ways that are not always visible on a term sheet. They affect how aggressively banks lend, how much documentation borrowers must provide, and how quickly conditions can change when the economy softens.

What lenders are watching more closely

Credit analysis for small businesses has become more granular. Lenders are increasingly focused on recurring revenue, customer retention, gross margins, and the reliability of bank deposits. They are also looking harder at how concentrated a business is in a single supplier, a handful of customers, or one local market. A restaurant with strong traffic but thin margins can be harder to finance than a software company with recurring subscriptions, even if the restaurant has been profitable for years. Similarly, a manufacturer with a single major buyer may face more scrutiny than a smaller firm with diversified accounts, because the lender has to think about what happens if that buyer delays payment or disappears.

Personal credit still matters too, especially for very small firms and first-time borrowers. Many lenders continue to use personal guarantees, which means the owner's household finances remain linked to the business. That can be frustrating for founders who think of the company as separate from their personal balance sheet, but it is still common practice because many small businesses do not have enough hard collateral to secure a loan on business assets alone. In practice, a business owner may need to improve both the company's financial profile and personal credit standing to access better terms.

This is also where documentation has become decisive. Strong bookkeeping, clean tax returns, up-to-date financial statements, and organized accounts receivable records can materially improve a borrower's odds. Lenders want to see not only that the business is viable, but that it is being managed with enough discipline to survive volatility. For owners who are still building that discipline, the topic connects closely with business operations, founders, and investment, because financing decisions increasingly reward operational clarity rather than growth stories alone.

The sectors most exposed to credit stress

Not all small businesses experience lending conditions the same way. Industries with variable demand, thin margins, inventory exposure, or heavy equipment needs tend to feel tighter credit conditions first. Retailers can face pressure from shifting consumer spending and inventory financing needs. Construction firms often need working capital to bridge payment timing gaps between projects. Transportation companies may be sensitive to fuel costs and equipment replacement cycles. Restaurants and hospitality businesses, meanwhile, can struggle when labor costs rise and sales fluctuate seasonally.

Technology and service firms are not immune, but they often have different financing profiles. A software startup may not need a large asset-backed loan, yet it can face difficulty if it lacks recurring revenue or if growth has slowed. Professional services firms may be profitable but still need credit to smooth payroll or fund expansion. In each case, the lender is trying to estimate whether today's earnings can support tomorrow's obligations. That uncertainty tends to widen the gap between businesses with predictable cash flow and those that depend on future sales momentum.

Geography also matters. Firms in fast-growing metro areas may have more financing options than those in smaller markets where local banking competition is limited. Businesses in regions affected by property weakness, labor shortages, or sector-specific downturns may also find lenders more cautious. These patterns are not unique to the U.S., but they are especially visible in a country where local and regional banks still play a major role in small business finance. For owners watching related macro trends, global markets and news coverage can provide useful context when local lending conditions shift quickly.

Why loan demand and loan supply can move in opposite directions

One of the most misunderstood parts of the current lending environment is that demand and supply do not always move together. Small businesses may want more credit because borrowing costs are high, cash flow is uneven, or expansion is expensive. At the same time, lenders may become less willing to extend credit because they see greater downside risk. That mismatch can create a feeling of scarcity even when there is no formal shortage of capital. Businesses that need financing most urgently are often the ones least likely to qualify on favorable terms.

This is why many owners are turning to a mix of financing sources rather than relying on a single bank line. Some use term loans for equipment, revolving credit for inventory, invoice financing for working capital, and revenue-based financing for short-term flexibility. That diversification can help, but it also increases complexity and can raise total borrowing costs if not managed carefully. The most financially resilient firms tend to match the type of financing to the purpose of the spending, instead of using expensive short-term credit to fund long-lived assets.

The broader capital market environment is relevant here too. When public markets are volatile, some lenders become more cautious about the outlook for borrowers in cyclical sectors. That is one reason stock markets can indirectly influence small business credit, even though most owners are not active market participants. Investor sentiment affects bank funding costs, private credit appetite, and the terms offered by nonbank lenders. The connection is not always immediate, but it is real.

What business owners can do to improve access

For many small businesses, better financing outcomes start long before the loan application is submitted. The first step is usually cash-flow visibility. Owners who can show a lender how revenue arrives, where costs are concentrated, and how repayment will be covered are in a stronger position than those relying on rough estimates. That means monthly financial statements, reconciled bank accounts, and realistic forecasts matter more than polished pitch decks. It also means owners should be prepared to explain any unusual swings in revenue, margins, or inventory.

The second step is understanding which lender type fits the need. A bank may be the right choice for a multi-year equipment purchase or a working-capital line tied to deposits. An SBA-backed loan may work better for a borrower with limited collateral but solid fundamentals. A fintech lender may be appropriate for a short-term gap that must be filled quickly, even if the price is higher. The wrong choice is often to accept the fastest offer without comparing the effective cost of capital. Business owners who are also evaluating digital tools may want to look at technology and artificial intelligence coverage, since underwriting, bookkeeping, and forecasting tools are becoming more automated and more useful.

The third step is reducing avoidable risk before applying. Paying down revolving balances, cleaning up tax issues, separating personal and business accounts, and organizing contracts can all improve a lender's confidence. For businesses that rely heavily on one or two customers, diversifying the revenue base can matter as much as improving the balance sheet. Owners should also be careful about stacking multiple short-term loans, which can create a repayment burden that looks manageable in isolation but becomes dangerous when combined. In a tighter market, the strongest applications are often the simplest ones: clear purpose, clear repayment source, and clear evidence that the business can absorb a setback.

What to watch next in the lending cycle

The next phase of small business lending will likely depend on a few linked factors: the direction of interest rates, the health of the labor market, deposit competition among banks, and whether credit losses remain contained. If rates ease meaningfully and inflation stays under control, some financing conditions could improve, especially for borrowers with decent but not exceptional credit. If growth slows or delinquencies rise, lenders may become even more cautious before they become more generous. In other words, small business credit is likely to remain selective rather than uniformly easy or uniformly tight.

That matters because small firms are still a major source of hiring, innovation, and local economic activity. When credit is available on workable terms, owners can invest in inventory, equipment, marketing, and staff. When it is not, they delay hiring, postpone expansion, or rely on more expensive forms of finance that can weaken margins. For readers tracking the intersection of business conditions and funding availability, the most useful lens is not whether credit exists in the abstract, but whether the current mix of lenders, rates, and underwriting standards supports productive growth.

The practical takeaway is straightforward: the lending market is still open, but it is less forgiving. Businesses with strong records, disciplined cash management, and realistic borrowing plans can still find capital. Those without those advantages may need to work harder, compare more options, and accept that the cheapest money is no longer easy money.

What Core Inflation Means for Business Costs and Pricing

Last updated by Editorial team at business-fact.com on Thursday 5 November 2026
Article Image for What Core Inflation Means for Business Costs and Pricing

What Core Inflation Means for Business Costs and Pricing

Core inflation is one of those economic measures that rarely matters in isolation, but it becomes highly relevant the moment a business has to set prices, negotiate contracts, manage payroll, or decide whether to invest. Unlike headline inflation, which moves with energy and food prices, core inflation strips out those volatile categories to give a clearer view of underlying price pressure. That distinction matters because persistent inflation in the parts of the economy businesses actually use every day tends to shape wage demands, supplier pricing, borrowing costs, and customer behavior more than a short-lived spike in gasoline or groceries. For companies trying to plan ahead, core inflation is less about the index itself and more about what it signals: whether higher costs are becoming embedded in the economy. For a broader macro lens, it sits alongside the news covered in economy, banking, and investment.

Why core inflation gets so much attention

Central banks, finance teams, and analysts watch core inflation because it tends to reveal whether price pressures are broadening beyond a few volatile categories. In the United States, the Federal Reserve follows measures such as the Consumer Price Index excluding food and energy and the Personal Consumption Expenditures price index, both of which help separate temporary shocks from more persistent inflation trends. The same logic appears in other major economies, including the euro area, the United Kingdom, and Canada, where official statistical agencies and central banks publish their own preferred measures. The headline number may grab attention, but core inflation is often the one that influences policy expectations, borrowing costs, and business confidence. Official sources such as the U.S. Bureau of Labor Statistics, the Federal Reserve, and the European Central Bank are useful starting points for understanding how these measures are constructed and why they move differently.

For businesses, the practical value of core inflation is that it often tracks the cost environment more closely than a single monthly jump in fuel or food. A restaurant may care deeply about food inflation, but a broader retail or services company may be more affected by rent, wages, insurance, transport, and financing costs, all of which can show up in underlying inflation trends. That is why core inflation is a better guide to whether price increases are likely to stick. It does not predict every cost line item, and it can miss some sector-specific pressures, but it is a useful signal of whether the inflationary environment is becoming more durable. That distinction also helps explain why businesses often monitor inflation data alongside labor-market reports from agencies such as the International Labour Organization and the Organisation for Economic Co-operation and Development, especially when wage growth is a major cost driver.

How core inflation filters through to business costs

Core inflation affects business costs in layers. The first layer is direct input costs: materials, components, packaging, services, and logistics tend to become more expensive when underlying inflation is elevated. The second layer is labor. If workers see broad price increases, wage negotiations often reflect that reality, especially in tight labor markets. The third layer is financing. Central banks usually respond to persistent inflation by keeping interest rates higher for longer, which raises the cost of debt, inventory financing, and working capital. Even firms that do not borrow heavily can feel the effect through slower demand, tighter credit standards, and a more cautious investment climate. This is why inflation is not just a consumer issue; it is an operating-cost issue that reaches into almost every decision a company makes.

The effect is not evenly distributed. Manufacturers can face higher input and freight costs before those pressures show up in consumer prices. Service businesses may feel more of the burden through wages, rent, and professional fees. Technology and software firms often have lower direct exposure to commodity swings, but they are not insulated from labor-market inflation or from customers who become more price sensitive. In that sense, core inflation is less about one industry than about the general temperature of the economy. Businesses that want to understand how inflation hits different sectors often pair macro data with sector-specific research from sources such as the World Bank and the International Monetary Fund, both of which regularly examine how inflation affects growth, investment, and corporate balance sheets across countries.

Pricing power is the real test

The most important question for many firms is not whether costs are rising, but whether they can pass those costs on. Core inflation matters because it helps reveal how much pricing power businesses may have. When underlying inflation is steady and consumer demand remains firm, companies often have more room to raise prices without losing too much volume. When inflation starts to ease, the opposite can happen: customers become more resistant, competitors become more aggressive on price, and businesses may have to absorb more of the cost increase themselves. Pricing power therefore depends not only on a company's own costs, but also on the broader inflation backdrop.

This is where the distinction between headline and core inflation becomes especially useful. A temporary energy shock may force a business to adjust prices quickly, but if core inflation remains subdued, customers may assume the increase is temporary and push back. If core inflation is elevated, price increases are more likely to feel normal across the market, making them easier to implement. That does not mean businesses can raise prices indefinitely. In many sectors, repeated price hikes eventually trigger trade-down behavior, lower volumes, or a shift to cheaper alternatives. Companies in marketing and business leadership roles often need to balance margin protection with customer retention, which is why inflation strategy is as much about positioning and communication as it is about arithmetic.

What businesses can do when core inflation stays elevated

When core inflation remains above target for an extended period, the best response is usually not a single price increase but a structured review of cost and revenue management. Companies often start by separating costs into what is controllable, what is contract-based, and what is externally determined. That makes it easier to identify where renegotiation, substitution, automation, or process redesign can reduce pressure. It also helps finance teams decide whether to lock in longer-term supplier agreements, adjust inventory strategy, or hedge certain exposures. In sectors with meaningful import exposure, exchange rates can amplify inflation, so businesses with international supply chains should pay attention to currency conditions as well as domestic price trends.

Labor strategy matters too. Persistent core inflation can lead to a wage-price dynamic in which employees seek pay increases to protect real income, while employers pass part of that cost into prices. Companies that depend heavily on skilled labor may need to respond with retention measures, productivity improvements, or compensation structures that are more flexible than across-the-board increases. For firms with thinner margins, the challenge is more severe: they may have to absorb some inflation, reduce discretionary spending, or rethink product mix. That is one reason inflation is so closely linked to employment conditions and business confidence, and why readers following these issues often move between employment, founders, and innovation coverage when they are trying to understand what comes next.

Why central banks matter to business pricing

Core inflation is not just an accounting concept; it is a policy signal. Central banks use it to judge whether inflation is likely to fade on its own or whether monetary policy needs to stay restrictive. When policymakers see persistent core inflation, they may keep interest rates elevated or delay cuts, which affects everything from corporate borrowing to consumer credit and commercial property financing. Businesses that depend on revolving credit, floating-rate debt, or frequent refinancing often feel this quickly. Even firms with strong cash positions can see demand soften if consumers face higher mortgage, auto, or card payments. In that sense, core inflation is one of the channels through which macro policy reaches day-to-day commercial decisions.

The policy response also matters because it can change the competitive environment. Higher rates tend to favor firms with strong margins, robust cash flow, and pricing discipline, while weaker businesses may struggle to keep up with rising financing and input costs. This dynamic is especially important in sectors that rely on leverage, such as real estate, construction, and parts of consumer discretionary retail. Broader market conditions also feed into business sentiment, which is why inflation data is often read alongside movements in stock markets and credit indicators. For a company planning capital expenditure or expansion, the question is not simply whether inflation is high, but whether it is high enough to keep monetary conditions tight for longer than expected.

Reading core inflation without overreacting to it

One common mistake is treating core inflation as a perfect measure of business reality. It is useful, but it is not complete. A firm whose costs are concentrated in energy, agricultural inputs, shipping, or imported goods may find that headline inflation or a sector-specific index tells a more relevant story. Core inflation is best understood as the broad backdrop, not the full map. It helps answer whether inflation is becoming embedded in the economy, but it does not replace detailed cost accounting or market-specific analysis. Businesses that rely too heavily on a single macro indicator can miss the fact that their own cost structure is moving differently from the economy as a whole.

The more practical approach is to combine inflation data with internal margin analysis, supplier intelligence, wage trends, and customer demand signals. That is especially true in periods when inflation is falling but still above historical norms, because disinflation can be uneven. Some costs may cool quickly while others remain sticky, and customers may resist price increases even as businesses continue to face elevated financing or labor expenses. Companies that follow global trends, technology shifts, and broader news events are often better positioned to spot these changes early and adjust before margins are squeezed.

The practical takeaway for business leaders

Core inflation matters because it helps reveal whether cost pressure is temporary noise or a more durable feature of the operating environment. For business leaders, that distinction affects pricing strategy, wage planning, supplier negotiations, borrowing decisions, and investment timing. When core inflation is firm, companies usually need more discipline around margins and more flexibility in pricing. When it is easing, they may have room to protect volume, rebuild customer trust, or delay price increases that would otherwise be necessary. Either way, the measure is most useful when it is treated as a signal rather than a forecast.

In practice, the businesses that manage inflation best are rarely the ones that simply raise prices the fastest. They are the ones that understand which costs are persistent, which are temporary, and which can be offset through productivity, product design, or smarter procurement. That is why core inflation remains a central number for executives, investors, and policymakers alike: it does not tell the whole story, but it tells enough of it to shape real decisions.