
How to Calculate Break-Even Points for a Growing Business
For a growing business, break-even analysis is not just a startup exercise or a line on a spreadsheet. It is one of the clearest ways to understand how much sales volume is needed before growth starts producing real profit rather than just more activity. That matters because scaling usually changes the math: fixed costs rise, variable costs shift, discounting may increase, and new channels can alter margins in ways that are easy to miss if the business is only watching revenue. A break-even point gives owners and managers a practical benchmark for deciding whether expansion is sustainable, how much cushion exists before losses appear, and which products or services are carrying the business. It is also a useful bridge between operational decisions and broader planning in areas such as business strategy, investment, and economy.
At its simplest, break-even is the point where total revenue equals total costs. Beyond that point, sales begin to generate profit; below it, the business is losing money. The concept sounds straightforward, but the details become more important as a business grows. A company with one product and a single sales channel can often estimate break-even with a basic formula. A company adding staff, entering new markets, or investing in technology may need to calculate several break-even points-by product line, by channel, or even by customer segment-to get a realistic view of performance. In practice, that means the question is not only "When do we break even?" but also "Which assumptions are driving that answer, and how quickly will they change as the business scales?"
The core formula and what it really measures
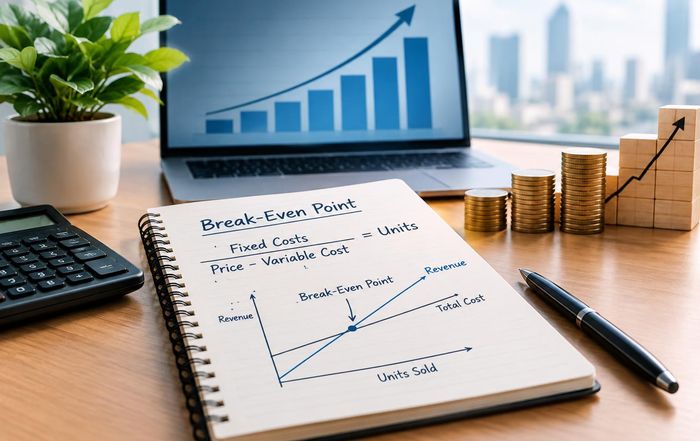
The standard break-even formula is:
Break-even units = Fixed costs ÷ (Selling price per unit - Variable cost per unit)
The denominator is the contribution margin per unit, which is the amount each sale contributes toward covering fixed costs and eventually producing profit. If a product sells for $100 and costs $60 to make and deliver, the contribution margin is $40. If fixed costs are $200,000, the business must sell 5,000 units to break even. In revenue terms, that same business breaks even at $500,000 in sales if the unit economics stay constant. This calculation is widely used because it translates an accounting idea into an operating target that managers can actually monitor.
But the formula only works well when the assumptions behind it are realistic. Fixed costs are not always perfectly fixed, especially in a growing business. Hiring a new sales team, signing a larger warehouse lease, or increasing software subscriptions can cause fixed costs to step up suddenly rather than gradually. Variable costs can also rise or fall with scale, supplier pricing, freight, payment processing, returns, or labor efficiency. For that reason, the formula should be treated as a decision tool rather than a prediction machine. Businesses that want a fuller operational picture often combine break-even analysis with banking and cash-flow planning, because a company can be technically above break-even and still run short of cash if payment timing is poor.
Separating fixed costs from variable costs
The first practical step is to classify costs correctly. Fixed costs are expenses that do not change directly with each additional unit sold over the relevant period, such as rent, core salaries, insurance, and many software subscriptions. Variable costs move with sales volume, such as raw materials, direct labor, packaging, shipping, commissions, and transaction fees. Some costs are mixed, meaning they contain both fixed and variable elements. A delivery fleet, for example, may have a base lease cost plus fuel and maintenance tied to usage. A marketing budget may include a fixed agency retainer and a variable performance spend. This distinction matters because a small classification error can move the break-even point enough to distort hiring, pricing, or expansion decisions.
A growing business should also be careful about which period it is analyzing. Monthly break-even is useful for cash planning and short-term management, while annual break-even is often better for strategic planning. If a business is seasonal, the timing of costs and sales matters as much as the totals. A retailer, restaurant, or event-driven company may break even on an annual basis but still need working capital to survive months of weak demand. That is where employment decisions become relevant: adding staff too early can push fixed costs higher before revenue has caught up, while delaying hiring too long can suppress growth and reduce service quality.
A simple example of break-even in a growing business
Imagine a subscription-based business selling a service at $50 per month per customer. Its variable cost per customer is $15, including support, payment processing, and service delivery. Fixed monthly costs are $35,000, covering salaries, office costs, software, and administration. The contribution margin per customer is $35. Dividing $35,000 by $35 means the business needs 1,000 customers to break even each month.
That example is simple, but it shows why growth changes the picture. If the business adds more support staff, the fixed cost base may rise to $50,000, pushing break-even to about 1,429 customers. If it improves automation and lowers variable cost to $12, the contribution margin rises to $38, and break-even falls to about 1,316 customers. If it raises prices to $55 while keeping demand stable, the contribution margin becomes $40 and break-even drops to 875 customers. In other words, break-even is not just a finance metric; it is a way to test how pricing, cost control, and operational efficiency interact. That is one reason founders often revisit it alongside founders discussions about scale, runway, and capital needs.
Why growing companies need more than a single break-even number
A single break-even point can be too blunt for a business that is expanding. Growth usually introduces multiple revenue streams, different margin profiles, and overhead that does not scale evenly. A software company may have one break-even point for self-serve customers and another for enterprise deals because sales cycles, onboarding, and support costs differ. A manufacturer may have one break-even point for domestic sales and another for export markets because logistics, tariffs, and compliance costs vary. A retailer may need separate calculations for online and physical channels because fulfillment and rent affect the economics differently. In these cases, the useful question is not whether the company as a whole breaks even, but which part of the business creates the margin that supports the rest.
This is especially important when a business is investing in new growth before the new revenue is fully visible. Marketing spend, product development, and hiring can all depress short-term margins while building future capacity. That is why break-even analysis should be paired with scenario planning. A base case, downside case, and growth case can show how many customers, orders, or contracts are needed under different assumptions. Businesses often combine that with market research from sources such as the U.S. Small Business Administration, OECD, and World Bank to understand whether demand conditions support the required volume.
The role of pricing, discounts, and unit economics
Pricing is one of the fastest ways to move a break-even point, but it is also one of the easiest levers to misread. A higher price can improve contribution margin, yet it may reduce volume if demand is sensitive. Discounts can stimulate sales, but they also lower the margin on every unit sold, which means the business must sell more to cover the same fixed cost base. For a growing business, the key question is not just whether a discount drives more revenue, but whether the additional volume improves total profit after accounting for the lower margin and any extra fulfillment cost.
Unit economics deserve special attention because they reveal whether growth is actually healthy. If a customer acquisition channel brings in sales at a loss, the business may still appear to be growing while moving farther from break-even. That can happen in subscription businesses, e-commerce, and marketplace models where acquisition is front-loaded and revenue arrives over time. In that setting, managers should compare customer acquisition cost, lifetime value, churn, and gross margin rather than relying on headline revenue alone. The same logic applies in marketing: a campaign that increases traffic is not necessarily improving break-even if it attracts low-margin customers or requires heavy discounting to convert.
Cash flow is not the same as break-even
One of the most common mistakes is assuming that break-even means the business is safe. It does not. Break-even is an accounting concept; cash flow is a liquidity concept. A company can be at or above break-even on paper and still struggle to pay suppliers, payroll, or taxes if customers pay slowly or inventory must be purchased in advance. Growing businesses often feel this gap most acutely because sales growth can consume cash before it produces it. Inventory builds, receivables expand, and hiring happens ahead of revenue recognition. That is why break-even analysis should sit alongside a cash-flow forecast rather than replace it.
This is also where stock markets and broader capital conditions matter indirectly. If external financing is expensive or harder to access, a business may need a lower break-even threshold and tighter working capital control to stay resilient. In stronger financing environments, management may tolerate a longer path to break-even in exchange for faster expansion. Either way, the underlying analysis should be honest about timing. A business that needs eight months of losses before reaching break-even is very different from one that can get there in two months, even if both have the same annual profit potential.
How to use break-even analysis when planning growth
The most useful way to apply break-even analysis is to treat it as a planning discipline, not a one-time calculation. Before hiring, launching a new product, opening a new location, or entering a new market, managers should estimate how the move changes fixed costs, variable costs, and expected volume. Then they should ask how much sales growth is needed to justify the added cost base and how long it may take to get there. That approach is particularly relevant in fast-moving sectors such as artificial intelligence and innovation, where product development and infrastructure spending can rise quickly before revenue stabilizes.
A practical planning process usually starts with the current break-even point, then models the effect of one change at a time. What happens if customer acquisition costs rise? What if suppliers raise prices by 5%? What if the company adds one more salesperson or opens a second office? What if conversion rates improve? These questions are not academic; they help leadership identify which assumptions are fragile and which are robust. Businesses that review these scenarios regularly are better positioned to avoid overexpansion, especially in industries where demand can shift quickly with consumer sentiment, interest rates, or competitive pressure. For companies with international exposure, it can also help to compare local conditions with broader global trends rather than assuming one market behaves like another.
When break-even should be recalculated
A growing business should revisit break-even whenever the cost structure changes materially, not just at year-end. That includes major price changes, new hiring, rent increases, supplier renegotiations, product launches, channel expansion, or shifts in customer mix. It is also worth recalculating after meaningful changes in the macro environment, such as inflation, wage pressure, or financing costs, because these can alter both fixed and variable cost assumptions. In some sectors, the break-even point can move faster than management expects simply because the business has become larger and more complex.
The point of recalculation is not to produce a perfect number. It is to keep management focused on the relationship between growth and profitability. Many businesses chase revenue growth because it is easy to measure, but revenue alone does not tell the full story. A company can grow quickly and still destroy value if margins erode or overhead outruns demand. A disciplined break-even framework helps prevent that mistake by showing how much growth is needed to support the business model, not just the sales target. For readers tracking broader market conditions, the same logic often applies across sectors covered by Business-Fact-from economy to investment and business.
For a growing company, break-even is best understood as a moving target. The calculation is simple, but the interpretation is strategic: it shows whether expansion is improving the business's economics or merely increasing its scale. That distinction is often what separates sustainable growth from expensive momentum.