Why Working Capital Management Matters for Business Growth

Last updated by Editorial team at business-fact.com on Monday 2 November 2026
Article Image for Why Working Capital Management Matters for Business Growth

Why Working Capital Management Matters for Business Growth

Working capital is often treated as a back-office accounting term, but for most businesses it is one of the clearest signals of whether growth is sustainable or merely expensive. A company can post rising sales and still run into cash trouble if customers pay slowly, inventory moves too sluggishly, or suppliers demand payment before revenue arrives. That is why working capital management sits at the intersection of finance, operations, and strategy. It affects whether a business can hire, restock, invest, borrow, and absorb shocks without constantly scrambling for cash.

For founders and operators, the issue is not just survival. Efficient working capital management can create room for expansion by reducing the amount of money tied up in day-to-day operations. That matters in sectors where margins are tight, demand is uneven, or growth is fast enough to strain internal systems. It also matters in periods of higher interest rates, when every dollar trapped in receivables or inventory carries a more visible cost. In that sense, working capital is not simply an accounting metric; it is a practical measure of how well a business converts activity into usable cash. For readers interested in broader financial context, the topic connects naturally with business strategy, banking, and investment decisions.

The basic idea behind working capital

At its simplest, working capital is the difference between current assets and current liabilities. Current assets usually include cash, accounts receivable, and inventory, while current liabilities include accounts payable and other short-term obligations. Positive working capital generally means a business has enough short-term resources to meet near-term obligations, though the quantity and quality of those resources matter just as much as the headline number. A company may look comfortable on paper while still being cash constrained if too much of its current assets are stuck in slow-moving stock or overdue invoices.

This is why working capital management is more useful than the balance-sheet figure alone. It asks how quickly the business collects cash, how efficiently it uses inventory, and how strategically it pays suppliers. Those decisions influence liquidity, supplier relationships, customer service, and ultimately growth capacity. The concept is widely used by finance professionals, and it is closely related to the broader measures discussed by organizations such as the International Monetary Fund, the World Bank, and the Bank for International Settlements, all of which regularly examine how credit conditions and liquidity affect economic activity.

Why growth often creates cash pressure

Growth usually consumes cash before it generates it. A business may need to buy more inventory, hire staff, increase marketing spend, or extend more generous payment terms to win larger customers. Revenue can rise quickly while cash lags behind, especially if the sales cycle is long or the customer base is concentrated in larger enterprises that pay on extended terms. That gap between selling and collecting is where many expanding businesses feel the strain.

This is one reason fast-growing companies sometimes fail despite strong demand. They expand operations faster than their cash conversion cycle can support. The problem is not necessarily poor sales; it is that the business is financing growth internally for longer than it can comfortably afford. Good working capital management shortens that gap. It helps a business grow without depending excessively on emergency credit lines, expensive short-term borrowing, or repeated owner injections. For companies watching broader economic conditions, the relationship between growth and liquidity is also shaped by trends in the economy and employment, both of which affect demand, wage costs, and collection risk.

The cash conversion cycle is where the pressure shows up

A useful way to understand working capital is through the cash conversion cycle, which measures how long cash is tied up between paying suppliers and collecting from customers. The cycle is shaped by three moving parts: days inventory outstanding, days sales outstanding, and days payable outstanding. If inventory sits too long, cash is locked in stock. If customers take too long to pay, cash remains trapped in receivables. If suppliers are paid too early, the business gives up a valuable source of short-term financing.

Improving any one of these elements can strengthen growth capacity. Faster collections improve liquidity. Better inventory planning reduces waste and markdowns. Negotiating supplier terms can preserve cash without necessarily damaging relationships, provided it is done transparently and responsibly. The best-managed businesses do not treat these levers in isolation; they align them with demand forecasts, procurement strategy, and customer terms. That is especially relevant in sectors shaped by technology and rapid demand shifts, where artificial intelligence and technology are increasingly used to improve forecasting, automate invoicing, and reduce operational friction.

Why it matters for financing and borrowing

Lenders and investors pay close attention to working capital because it reveals how much short-term strain a business can absorb. A company with disciplined receivables, controlled inventory, and predictable payables is generally easier to finance than one that relies on constant borrowing to bridge operating gaps. Banks often view working capital as a core indicator of credit quality because it shows whether a business can service obligations from ordinary operations rather than from one-off injections. That is one reason the topic matters not only to management teams but also to those following banking trends and stock markets, where liquidity discipline often influences valuations and lending appetite.

The cost of poor working capital management becomes more visible when rates rise or credit conditions tighten. In those periods, businesses with weak cash discipline can find refinancing more expensive or less available. By contrast, companies that manage receivables and inventory well may have more negotiating power with lenders and suppliers. This does not mean they never borrow; it means borrowing can support strategic expansion rather than patching avoidable cash gaps. For a broader view of how capital is allocated across businesses and markets, investment and global conditions both matter.

Operational discipline can be a growth advantage

Working capital is often discussed as a finance function, but the biggest improvements usually come from operational decisions. Sales teams influence payment terms. Procurement teams affect inventory levels and supplier timing. Customer service affects dispute resolution, which in turn affects collections. Even product design can influence working capital if it changes how much stock must be held or how complex the supply chain becomes. In other words, the balance sheet reflects choices made across the business, not just in the finance department.

This is where management discipline becomes a competitive advantage. A business that forecasts demand accurately, invoices promptly, and keeps inventory aligned with actual sales can grow with less friction than a rival that reacts late to demand changes. The difference may not always show up immediately in revenue, but it often appears in resilience. Businesses with stronger cash discipline can respond faster to opportunities, tolerate delays, and avoid making strategic decisions under pressure. That is particularly important for founders balancing expansion with execution, a theme that often overlaps with founders coverage and broader innovation strategy.

The risks of neglecting working capital

Ignoring working capital can create a misleading picture of success. A company may celebrate higher sales while quietly stretching payables, accumulating overdue receivables, or filling warehouses with stock that is not moving. Eventually, those pressures can lead to late payments, strained supplier relationships, missed payroll risk, or the need to accept expensive financing just to keep operations running. Once that cycle starts, management time often shifts from growth to damage control.

There is also a strategic cost. Businesses that run too close to the edge may pass on good opportunities because they lack the liquidity to act quickly. They may be forced to choose between growth and stability, when ideally they should be able to pursue both. In sectors exposed to seasonality, trade disruptions, or volatile demand, the risk is even greater. Companies with stronger working capital buffers are better positioned to absorb shocks, whether those come from supply chain disruption, customer defaults, or sudden changes in consumer behavior. For businesses operating in environmentally sensitive or regulated sectors, sustainable practices can also affect inventory, sourcing, and compliance costs, which in turn influence working capital needs.

What strong working capital management looks like in practice

The most effective businesses treat working capital as a living system. They monitor cash flow frequently rather than waiting for month-end reports. They review customer payment behavior, not just invoice totals. They manage inventory by demand, not habit. They negotiate supplier terms in ways that support both cash flow and long-term relationships. And they use forecasting to anticipate when growth will require extra liquidity, rather than discovering the problem after cash tightens.

Technology can make this far easier. Automated invoicing, real-time inventory tracking, and predictive analytics can reduce errors and improve visibility. Artificial intelligence tools are increasingly being used to forecast demand, identify late-paying customers, and improve purchasing decisions. But tools alone do not solve the issue. The underlying discipline still matters: clear credit policies, realistic sales forecasts, and management accountability for cash conversion. Businesses that combine data with operational rigor are usually better positioned to scale without unnecessary strain.

Why it matters across different business models

The importance of working capital varies by industry, but it rarely disappears. Retailers and wholesalers need to fund inventory. Manufacturers must manage raw materials, work in progress, and finished goods. Service firms may have less inventory but can still face receivables pressure if clients pay slowly. Startups often have the most fragile position because they are trying to grow while building predictable revenue. Even profitable companies can run into trouble if their growth model requires too much cash before payment is received.

That is why working capital is best understood as a growth enabler rather than just a defensive metric. It allows businesses to expand in a controlled way, support customers reliably, and make decisions from a position of strength. In a volatile environment, that flexibility can matter as much as margin. A company that understands its cash cycle can often grow more steadily than one that chases revenue without attention to timing. For readers following the broader economic picture, the relationship between liquidity, credit, and expansion is one of the most practical links between business, economy, and global markets.

Working capital management matters because growth is not just about selling more. It is about turning sales into cash, cash into capacity, and capacity into durable expansion. Businesses that master that sequence tend to have more options, more resilience, and fewer surprises when conditions change.

How Skills-Based Hiring Is Changing Recruitment Worldwide

Last updated by Editorial team at business-fact.com on Sunday 1 November 2026
Article Image for How Skills-Based Hiring Is Changing Recruitment Worldwide

How Skills-Based Hiring Is Changing Recruitment Worldwide

Recruitment is moving away from a narrow focus on degrees, job titles, and linear career paths. In its place, many employers are trying to identify what candidates can actually do, not just where they studied or which company names appear on a résumé. That shift is often described as skills-based hiring, and it is changing how organizations assess talent, how candidates present themselves, and how labor markets function across sectors. The change is not uniform, and it is not complete, but it is far more than a passing trend. It reflects a broader rethinking of how work gets done in an economy shaped by fast-moving technology, demographic pressure, and persistent talent shortages. For well educated individuals following broader labor-market shifts, it connects closely with original and factual themes covered in employment, business, and technology.

The appeal is straightforward. Employers want faster, more accurate ways to match people to work. Job seekers want fairer access to opportunities that may have been blocked by rigid credential requirements. Governments and workforce agencies want higher labor-force participation and better alignment between education and employment. Yet the transition also raises practical questions: how do employers verify skills at scale, which roles can truly be hired this way, and what happens to traditional signals such as degrees, certifications, and prior employers? Those questions matter because skills-based hiring is not just a human resources slogan. It is changing the mechanics of recruitment in global labor markets, from entry-level roles to specialized professional work.

Why employers are rethinking credentials

The most important force behind skills-based hiring is the mismatch between conventional hiring filters and actual job performance. A degree can indicate persistence, exposure to structured learning, and baseline knowledge, but it does not necessarily prove that someone can perform a specific task in a specific workplace. In many industries, employers have discovered that academic credentials are an imperfect proxy for capability, especially when roles are evolving quickly. This is particularly visible in digital functions, where practical familiarity with software, data tools, and workflow automation can matter more than a formal major. It is also evident in sectors facing chronic shortages, including healthcare support, logistics, manufacturing, and customer operations. Organizations that want to widen their candidate pool are increasingly asking whether a degree requirement is essential or simply habitual.

This shift has been reinforced by labor-market data and by policy attention. The OECD has repeatedly highlighted the importance of adult skills, training, and matching in modern labor markets, while the ILO has emphasized changing employment patterns and the need for more inclusive pathways into work. In the United States, the U.S. Bureau of Labor Statistics continues to show how occupational demand changes over time, while employers in Europe and Asia face similar pressures from aging populations and digital transformation. The result is a growing preference for evidence of competence over pedigree. For many recruiters, that means restructuring job descriptions, interview stages, and assessment tools so that candidates are screened on practical abilities rather than on legacy assumptions.

What skills-based hiring looks like in practice

In practice, skills-based hiring can mean several different things. At one end of the spectrum, it simply means rewriting job ads to remove unnecessary degree requirements and to describe the actual capabilities needed for the role. At the other end, it involves structured assessments, work samples, simulations, portfolio reviews, or task-based interviews that test whether candidates can do the work before an offer is made. Some employers use skills taxonomies to map roles more precisely, while others build internal talent marketplaces so employees can move into new roles based on demonstrated skills. The common thread is that recruitment becomes more evidence-driven and less dependent on proxies.

This approach is spreading because it can improve both speed and quality of hiring when implemented well. A candidate who has built a relevant portfolio, completed a recognized bootcamp, or accumulated experience in adjacent roles may be a better fit than someone with a prestigious credential but little practical exposure. That logic is especially relevant in fields such as artificial intelligence, where tools and workflows are changing quickly enough that yesterday's academic preparation may not fully reflect today's needs. It is also influencing how employers think about internal mobility: rather than hiring externally for every gap, companies can identify employees who already have transferable skills and train them into new roles. For organizations focused on resilience, that can be as valuable as external recruiting.

The role of technology in accelerating the shift

Recruitment technology has made skills-based hiring easier to scale, but it has also introduced new risks. Applicant tracking systems, skills ontologies, and AI-assisted screening tools can help employers compare candidates more consistently, identify transferable experience, and reduce the time spent on manual résumé review. Used well, they can broaden the talent pool and make hiring more transparent. Used poorly, they can simply automate old biases in a new format. That is why the quality of the underlying data matters so much. If a system is trained on historical hiring patterns that favored certain schools, employers, or job titles, it may reproduce those preferences unless recruiters deliberately redesign the process.

The broader technology ecosystem is also pushing this change. Digital credentials, online learning platforms, and remote work tools have made it easier for candidates to show what they know outside traditional institutions. Platforms such as LinkedIn have helped normalize public skills profiles, while major cloud and software companies have promoted certification pathways that are more modular than a four-year degree. At the same time, employers are under pressure to be more precise about what a skill actually means. A label like "data analysis" or "project management" can be too vague to support hiring decisions unless it is tied to concrete tasks, proficiency levels, and workplace context. That is why many organizations are moving toward more granular capability frameworks rather than broad job-family descriptions.

Where the model works best, and where it is harder to apply

Skills-based hiring is most effective when job performance can be observed through tasks, outputs, or structured simulations. That makes it especially useful in software development, sales, operations, design, technical support, and many frontline roles. It can also work well in public-sector hiring and large enterprises that need to recruit at scale across many locations. In these settings, task-based assessment can reduce overreliance on résumé screening and open opportunities to candidates who have learned through apprenticeships, career changes, military service, caregiving experience, or informal work. It can also help employers identify nontraditional talent in markets where formal qualifications are unevenly distributed.

The model is harder to apply in roles where credentials are legally required, where professional licensing is central, or where judgment depends on deep domain knowledge that is difficult to test quickly. Medicine, law, engineering, and regulated financial functions still depend on formal qualifications in many jurisdictions, and for good reason. Even in less regulated fields, some jobs combine technical competence with tacit knowledge, relationship management, and organizational fit in ways that are difficult to reduce to a checklist. That is why skills-based hiring should not be mistaken for credential elimination. In many cases, the best approach is a blended one: keep the credentials that genuinely protect quality or compliance, but stop using them as a default filter when they are not essential. That distinction is especially relevant in banking, investment, and other sectors where trust, regulation, and risk management still matter.

Implications for job seekers and education providers

For job seekers, the shift is both promising and demanding. It can open doors for people without elite degrees, but it also raises the bar for demonstrating practical competence. Candidates increasingly need to present evidence in forms that recruiters can evaluate quickly: project portfolios, work samples, skills tests, certifications, freelance outcomes, or documented achievements. That changes how resumes are written and how careers are narrated. Instead of listing employers and responsibilities alone, applicants may need to show how they solved problems, improved processes, or delivered measurable results. This is particularly important for people changing industries, returning to work after a break, or entering the labor market through alternative routes.

Education providers are under pressure to adapt as well. Universities, vocational schools, and private training organizations are being asked to prove that their programs lead to usable skills, not just academic completion. That is encouraging more partnerships between employers and educators, more modular learning, and more emphasis on work-integrated experience. The trend also intersects with debates about the value of higher education, though the conclusion is not that degrees have become irrelevant. Rather, their value is being judged more selectively. A degree may still offer broad knowledge, social capital, and access to networks, but employers are increasingly asking whether it is the right signal for a given role. That shift is likely to influence curriculum design, apprenticeship expansion, and employer-sponsored training for years to come.

The fairness question is real, but so are the risks

Supporters often describe skills-based hiring as a more equitable model, and there is truth in that. Removing unnecessary degree barriers can expand access for capable candidates who were excluded by cost, geography, or family background. It can also help employers reach underrepresented groups and make hiring more inclusive in practice rather than in rhetoric. Organizations such as WEF and World Bank have both highlighted the importance of reskilling and labor-market inclusion in a rapidly changing economy. Yet fairness is not guaranteed simply because a hiring process uses the word "skills." If assessments are poorly designed, they can advantage candidates with more time, money, or coaching. If employers overvalue polished portfolios or specific software familiarity, they may simply replace one gatekeeping mechanism with another.

There is also a risk of fragmentation. Without common standards, "skills-based hiring" can mean very different things from one employer to another, making it hard for candidates to know how to prepare and hard for employers to compare applicants consistently. This is one reason public institutions and industry groups are trying to define skills more clearly. Standards bodies and workforce organizations, including ISO and NIST in adjacent areas of measurement and digital infrastructure, illustrate the broader importance of common frameworks when markets need comparability. In recruitment, the same logic applies: if skills are to become a true hiring currency, they need clearer definitions, more reliable assessment methods, and greater portability across employers and borders.

What global adoption is likely to change next

Over the next few years, the biggest change may not be the disappearance of degrees but the gradual decline of degree-first screening. In many markets, employers will continue to value formal education, especially for complex or regulated roles, while using skills-based methods to widen the pool and improve selection. That hybrid model is likely to become the norm. Large employers will also keep investing in internal talent mobility, because it is often cheaper and faster to redeploy current workers than to recruit externally. Governments may encourage the shift through workforce policy, public hiring reforms, and support for adult learning. And as artificial intelligence changes more jobs, the ability to identify transferable skills will become even more important than the ability to match candidates to fixed job titles.

For recruitment teams, the practical challenge is not whether to adopt skills-based hiring, but how to do it without losing rigor. That means defining the skills that matter, validating the assessments used to measure them, and making sure the process is fair, scalable, and transparent. For candidates, it means learning to show evidence of ability in forms that are easy to verify. For education providers, it means designing learning that employers can trust. The organizations that adapt fastest will probably be the ones that treat skills not as a buzzword, but as a more precise way to understand talent. In that sense, the shift is less about abandoning the old hiring model than about making recruitment more honest about what work actually requires.

What Stock Market Breadth Reveals About Investor Confidence

Last updated by Editorial team at business-fact.com on Saturday 31 October 2026
Article Image for What Stock Market Breadth Reveals About Investor Confidence

What Stock Market Breadth Reveals About Investor Confidence

Stock prices can rise while investor confidence quietly weakens, and that is exactly why market breadth matters. Breadth is a way of checking how many stocks are participating in a move, rather than simply watching the major indexes. When a rally is powered by a broad set of winners across sectors and market caps, it often suggests that investors are willing to take risk more widely. When only a narrow group of large names is carrying the market, confidence may be more fragile than the headline index level implies. For readers following stock markets, breadth is one of the most useful lenses for separating durable optimism from concentrated enthusiasm.

Breadth is the market's participation test

At its simplest, market breadth asks a basic question: are many stocks moving together, or only a few? Common breadth measures include the number of advancing versus declining stocks, the share of stocks trading above key moving averages, new highs and new lows, and equal-weighted index performance. These indicators are widely used by traders, portfolio managers, and market strategists because they help reveal whether a trend is broad-based or narrowly led. The New York Stock Exchange and Nasdaq both provide market data that investors use to monitor this kind of participation, while financial data providers such as S&P Dow Jones Indices and FTSE Russell publish index methodologies that make the difference between cap-weighted and equal-weighted performance easier to see.

Broad participation usually means more than just a healthy chart. It often reflects a wider willingness among investors to move money into cyclicals, smaller companies, industrials, financials, and other segments that tend to benefit when confidence improves. Narrow participation, by contrast, can indicate that investors are hiding in a small number of perceived safe or dominant companies. That does not automatically mean the market is about to fall, but it does suggest the rally may be more dependent on a few leaders than on a genuine improvement in risk appetite. For investors in economy-sensitive sectors, that distinction can matter as much as the index level itself.

Why breadth often says more than the headline index

A market index can be misleading because of how it is built. In a cap-weighted index, the biggest companies have the greatest influence, so a handful of mega-cap stocks can lift the entire benchmark even if a majority of constituents are flat or falling. That is one reason analysts often compare cap-weighted indexes with equal-weighted versions. The equal-weighted approach gives each stock a similar influence, making it easier to see whether the average company is participating. When the equal-weighted index lags badly behind the standard benchmark, it often signals that investor confidence is concentrated rather than widespread.

This distinction became especially important in the era of dominant technology platforms, when a small number of large names could drive a large share of index gains. Investors who only watch the S&P 500 or Nasdaq Composite may miss whether the rest of the market is confirming the move. That is why many professionals also look at data from the Federal Reserve, the Bank for International Settlements, and major market data vendors when assessing whether asset prices are being supported by broader financial conditions or by a narrow risk-on trade. For those tracking investment trends, breadth can help distinguish a durable bull market from one that depends on a few crowded trades.

What improving breadth usually tells investors

When breadth improves alongside rising indexes, it often suggests confidence is spreading through the market. Investors may be gaining conviction that earnings are stabilizing, inflation is easing, interest rates are becoming more manageable, or the economic outlook is less uncertain than before. In those periods, leadership often rotates away from defensive names and into more economically sensitive areas such as small caps, industrials, consumer discretionary stocks, and banks. Broader participation can also indicate that managers are deploying cash more aggressively rather than waiting for clearer signals.

This is one reason breadth is watched closely during recoveries after stress periods. If the number of stocks making new highs expands steadily, and if more sectors begin to outperform, the move is usually viewed as healthier than a rally powered by only a few stocks. That said, breadth is not a perfect timing tool. It can improve before the economy visibly strengthens, or it can strengthen temporarily and then fade. Still, a broadening market often aligns with rising confidence among institutions and retail investors alike, especially when credit spreads, earnings revisions, and employment data are also improving. Readers interested in the labor side of sentiment can also look at employment trends, since job stability often supports spending and risk-taking.

When weak breadth warns that confidence is thinner than it looks

Weak breadth does not always mean a downturn is imminent, but it can be an early warning that the market is leaning too heavily on a small leadership group. If fewer stocks are advancing, fewer sectors are joining the rally, and new highs are not broadening out, optimism may be more tentative than the index suggests. Investors may still be comfortable owning the market's dominant names, but they may not yet trust the broader economy or earnings backdrop enough to buy more cyclically exposed stocks.

That pattern can be especially important during periods when monetary policy is restrictive or when economic data is mixed. In such environments, a few large, high-quality companies may continue to attract capital because investors value balance-sheet strength and earnings visibility. Meanwhile, smaller or more leveraged companies may lag because financing costs remain high or demand is uncertain. For anyone following banking, technology, or artificial intelligence stocks, breadth can show whether enthusiasm is broadening into the rest of the market or staying trapped in one theme.

The signals professionals watch together, not in isolation

Breadth is most useful when read alongside other indicators. Advance-decline lines, new highs versus new lows, sector rotation, volume trends, volatility, and credit conditions can all help confirm or challenge the message from the price action. A rally with improving breadth and rising volume generally carries more credibility than one with weak participation and thin trading. Likewise, if breadth deteriorates while volatility stays subdued, investors may be underpricing the risk of a sharper rotation later on.

Professional investors also pay attention to market internals across different time horizons. Short-term breadth can be noisy, especially around earnings season, central bank meetings, or major geopolitical events. Longer-term breadth trends are often more informative because they show whether leadership is expanding over weeks or months rather than days. That is why analysts often examine breadth across U.S. markets, but also across global equities, especially when capital flows are shifting between regions. Institutions such as the International Monetary Fund, the World Bank, and the Organisation for Economic Co-operation and Development are useful reference points for the macro backdrop that can influence how broad or narrow market confidence becomes.

Breadth, confidence, and the psychology of investing

Investor confidence is not just a mood; it is reflected in how widely capital is deployed. When confidence rises, investors tend to become more willing to own companies with less obvious safety, weaker near-term earnings, or higher sensitivity to the economic cycle. Breadth captures that behavioral shift because it shows whether money is moving beyond the obvious winners. In that sense, breadth is a market-level expression of trust: trust in earnings, trust in growth, trust in policy stability, and trust that risk is being rewarded fairly.

That psychological dimension also explains why breadth can deteriorate even while news flow appears positive. If investors think the gains are too concentrated, too dependent on a small group of firms, or too disconnected from the real economy, they may stay cautious. The result is a market that looks strong on the surface but feels narrow underneath. For businesses and investors trying to understand sentiment, that gap matters. It can affect fundraising conditions, merger appetite, hiring plans, and capital spending, especially in sectors that depend on broad risk tolerance. Readers exploring business and founders topics will often see the same pattern in private markets: confidence is rarely just about valuation; it is about how widely people believe growth can continue.

What retail investors can realistically take from breadth

Breadth should not be treated as a magic signal, but it is a practical tool for avoiding overconfidence. If an index is rising while participation is weak, investors may want to ask whether they are buying a broad opportunity or a narrow trade. If breadth is improving, that can add confidence that the move is being supported by a wider base of demand. For long-term investors, the main value of breadth is not prediction so much as context. It helps explain why a rally may feel sturdy or fragile, and it can prevent people from assuming that a headline index tells the whole story.

It is also useful for portfolio construction. Investors who see improving breadth may become more comfortable diversifying beyond a few mega-cap leaders, while those who see deteriorating breadth may prefer to review exposure to smaller, more cyclical, or more leveraged holdings. None of this removes the need for fundamental analysis, but it does add a layer of market awareness that can improve timing and risk management. In a world where a few stocks can dominate returns, breadth remains one of the clearest ways to answer a deceptively simple question: is confidence spreading, or is the market being held up by a narrow crowd of favorites?

For clever individuals tracking shifts in sentiment across sectors, breadth is one of the most useful reminders that markets are more than index levels. It is often the difference between a rally that merely looks strong and one that is actually being shared by the broader market.

How to Calculate Break-Even Points for a Growing Business

Last updated by Editorial team at business-fact.com on Friday 30 October 2026
Article Image for How to Calculate Break-Even Points for a Growing Business

How to Calculate Break-Even Points for a Growing Business

For a growing business, break-even analysis is not just a startup exercise or a line on a spreadsheet. It is one of the clearest ways to understand how much sales volume is needed before growth starts producing real profit rather than just more activity. That matters because scaling usually changes the math: fixed costs rise, variable costs shift, discounting may increase, and new channels can alter margins in ways that are easy to miss if the business is only watching revenue. A break-even point gives owners and managers a practical benchmark for deciding whether expansion is sustainable, how much cushion exists before losses appear, and which products or services are carrying the business. It is also a useful bridge between operational decisions and broader planning in areas such as business strategy, investment, and economy.

At its simplest, break-even is the point where total revenue equals total costs. Beyond that point, sales begin to generate profit; below it, the business is losing money. The concept sounds straightforward, but the details become more important as a business grows. A company with one product and a single sales channel can often estimate break-even with a basic formula. A company adding staff, entering new markets, or investing in technology may need to calculate several break-even points-by product line, by channel, or even by customer segment-to get a realistic view of performance. In practice, that means the question is not only "When do we break even?" but also "Which assumptions are driving that answer, and how quickly will they change as the business scales?"

The core formula and what it really measures

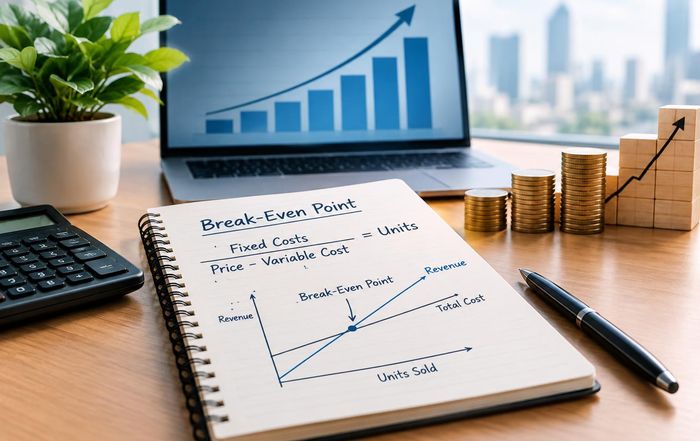
The standard break-even formula is:

Break-even units = Fixed costs ÷ (Selling price per unit - Variable cost per unit)

The denominator is the contribution margin per unit, which is the amount each sale contributes toward covering fixed costs and eventually producing profit. If a product sells for $100 and costs $60 to make and deliver, the contribution margin is $40. If fixed costs are $200,000, the business must sell 5,000 units to break even. In revenue terms, that same business breaks even at $500,000 in sales if the unit economics stay constant. This calculation is widely used because it translates an accounting idea into an operating target that managers can actually monitor.

But the formula only works well when the assumptions behind it are realistic. Fixed costs are not always perfectly fixed, especially in a growing business. Hiring a new sales team, signing a larger warehouse lease, or increasing software subscriptions can cause fixed costs to step up suddenly rather than gradually. Variable costs can also rise or fall with scale, supplier pricing, freight, payment processing, returns, or labor efficiency. For that reason, the formula should be treated as a decision tool rather than a prediction machine. Businesses that want a fuller operational picture often combine break-even analysis with banking and cash-flow planning, because a company can be technically above break-even and still run short of cash if payment timing is poor.

Separating fixed costs from variable costs

The first practical step is to classify costs correctly. Fixed costs are expenses that do not change directly with each additional unit sold over the relevant period, such as rent, core salaries, insurance, and many software subscriptions. Variable costs move with sales volume, such as raw materials, direct labor, packaging, shipping, commissions, and transaction fees. Some costs are mixed, meaning they contain both fixed and variable elements. A delivery fleet, for example, may have a base lease cost plus fuel and maintenance tied to usage. A marketing budget may include a fixed agency retainer and a variable performance spend. This distinction matters because a small classification error can move the break-even point enough to distort hiring, pricing, or expansion decisions.

A growing business should also be careful about which period it is analyzing. Monthly break-even is useful for cash planning and short-term management, while annual break-even is often better for strategic planning. If a business is seasonal, the timing of costs and sales matters as much as the totals. A retailer, restaurant, or event-driven company may break even on an annual basis but still need working capital to survive months of weak demand. That is where employment decisions become relevant: adding staff too early can push fixed costs higher before revenue has caught up, while delaying hiring too long can suppress growth and reduce service quality.

A simple example of break-even in a growing business

Imagine a subscription-based business selling a service at $50 per month per customer. Its variable cost per customer is $15, including support, payment processing, and service delivery. Fixed monthly costs are $35,000, covering salaries, office costs, software, and administration. The contribution margin per customer is $35. Dividing $35,000 by $35 means the business needs 1,000 customers to break even each month.

That example is simple, but it shows why growth changes the picture. If the business adds more support staff, the fixed cost base may rise to $50,000, pushing break-even to about 1,429 customers. If it improves automation and lowers variable cost to $12, the contribution margin rises to $38, and break-even falls to about 1,316 customers. If it raises prices to $55 while keeping demand stable, the contribution margin becomes $40 and break-even drops to 875 customers. In other words, break-even is not just a finance metric; it is a way to test how pricing, cost control, and operational efficiency interact. That is one reason founders often revisit it alongside founders discussions about scale, runway, and capital needs.

Why growing companies need more than a single break-even number

A single break-even point can be too blunt for a business that is expanding. Growth usually introduces multiple revenue streams, different margin profiles, and overhead that does not scale evenly. A software company may have one break-even point for self-serve customers and another for enterprise deals because sales cycles, onboarding, and support costs differ. A manufacturer may have one break-even point for domestic sales and another for export markets because logistics, tariffs, and compliance costs vary. A retailer may need separate calculations for online and physical channels because fulfillment and rent affect the economics differently. In these cases, the useful question is not whether the company as a whole breaks even, but which part of the business creates the margin that supports the rest.

This is especially important when a business is investing in new growth before the new revenue is fully visible. Marketing spend, product development, and hiring can all depress short-term margins while building future capacity. That is why break-even analysis should be paired with scenario planning. A base case, downside case, and growth case can show how many customers, orders, or contracts are needed under different assumptions. Businesses often combine that with market research from sources such as the U.S. Small Business Administration, OECD, and World Bank to understand whether demand conditions support the required volume.

The role of pricing, discounts, and unit economics

Pricing is one of the fastest ways to move a break-even point, but it is also one of the easiest levers to misread. A higher price can improve contribution margin, yet it may reduce volume if demand is sensitive. Discounts can stimulate sales, but they also lower the margin on every unit sold, which means the business must sell more to cover the same fixed cost base. For a growing business, the key question is not just whether a discount drives more revenue, but whether the additional volume improves total profit after accounting for the lower margin and any extra fulfillment cost.

Unit economics deserve special attention because they reveal whether growth is actually healthy. If a customer acquisition channel brings in sales at a loss, the business may still appear to be growing while moving farther from break-even. That can happen in subscription businesses, e-commerce, and marketplace models where acquisition is front-loaded and revenue arrives over time. In that setting, managers should compare customer acquisition cost, lifetime value, churn, and gross margin rather than relying on headline revenue alone. The same logic applies in marketing: a campaign that increases traffic is not necessarily improving break-even if it attracts low-margin customers or requires heavy discounting to convert.

Cash flow is not the same as break-even

One of the most common mistakes is assuming that break-even means the business is safe. It does not. Break-even is an accounting concept; cash flow is a liquidity concept. A company can be at or above break-even on paper and still struggle to pay suppliers, payroll, or taxes if customers pay slowly or inventory must be purchased in advance. Growing businesses often feel this gap most acutely because sales growth can consume cash before it produces it. Inventory builds, receivables expand, and hiring happens ahead of revenue recognition. That is why break-even analysis should sit alongside a cash-flow forecast rather than replace it.

This is also where stock markets and broader capital conditions matter indirectly. If external financing is expensive or harder to access, a business may need a lower break-even threshold and tighter working capital control to stay resilient. In stronger financing environments, management may tolerate a longer path to break-even in exchange for faster expansion. Either way, the underlying analysis should be honest about timing. A business that needs eight months of losses before reaching break-even is very different from one that can get there in two months, even if both have the same annual profit potential.

How to use break-even analysis when planning growth

The most useful way to apply break-even analysis is to treat it as a planning discipline, not a one-time calculation. Before hiring, launching a new product, opening a new location, or entering a new market, managers should estimate how the move changes fixed costs, variable costs, and expected volume. Then they should ask how much sales growth is needed to justify the added cost base and how long it may take to get there. That approach is particularly relevant in fast-moving sectors such as artificial intelligence and innovation, where product development and infrastructure spending can rise quickly before revenue stabilizes.

A practical planning process usually starts with the current break-even point, then models the effect of one change at a time. What happens if customer acquisition costs rise? What if suppliers raise prices by 5%? What if the company adds one more salesperson or opens a second office? What if conversion rates improve? These questions are not academic; they help leadership identify which assumptions are fragile and which are robust. Businesses that review these scenarios regularly are better positioned to avoid overexpansion, especially in industries where demand can shift quickly with consumer sentiment, interest rates, or competitive pressure. For companies with international exposure, it can also help to compare local conditions with broader global trends rather than assuming one market behaves like another.

When break-even should be recalculated

A growing business should revisit break-even whenever the cost structure changes materially, not just at year-end. That includes major price changes, new hiring, rent increases, supplier renegotiations, product launches, channel expansion, or shifts in customer mix. It is also worth recalculating after meaningful changes in the macro environment, such as inflation, wage pressure, or financing costs, because these can alter both fixed and variable cost assumptions. In some sectors, the break-even point can move faster than management expects simply because the business has become larger and more complex.

The point of recalculation is not to produce a perfect number. It is to keep management focused on the relationship between growth and profitability. Many businesses chase revenue growth because it is easy to measure, but revenue alone does not tell the full story. A company can grow quickly and still destroy value if margins erode or overhead outruns demand. A disciplined break-even framework helps prevent that mistake by showing how much growth is needed to support the business model, not just the sales target. For readers tracking broader market conditions, the same logic often applies across sectors covered by Business-Fact-from economy to investment and business.

For a growing company, break-even is best understood as a moving target. The calculation is simple, but the interpretation is strategic: it shows whether expansion is improving the business's economics or merely increasing its scale. That distinction is often what separates sustainable growth from expensive momentum.

AI Governance for Modern Business Leaders

Last updated by Editorial team at business-fact.com on Thursday 29 October 2026
Article Image for AI Governance for Modern Business Leaders

AI Governance for Modern Business Leaders

Why AI Governance Has Become a Board-Level Priority!

As artificial intelligence has shifted from a peripheral technology experiment to a core driver of competitive advantage in virtually every major industry, from financial services and healthcare to manufacturing, retail, logistics and professional services. For the readership here, this transition has elevated AI governance from a technical concern handled by data science teams to a strategic, enterprise-wide discipline that now sits firmly on the agendas of boards, CEOs and executive committees in leading organizations across North America, Europe, Asia and beyond.

The acceleration of generative AI, large language models and autonomous decision systems has transformed how businesses design products, price services, manage risk, allocate capital and interact with customers. Yet this same acceleration has introduced new classes of operational, legal, ethical, security and reputational risks that cannot be contained by traditional IT governance alone. Regulators, investors, customers and employees increasingly expect that organizations deploying AI will demonstrate clear accountability, robust oversight, transparent practices and credible safeguards. For executives responsible for core business strategy, AI governance has therefore become inseparable from corporate governance itself.

In this environment, AI governance is best understood not as a compliance checkbox, but as a management system that defines how an organization selects, designs, deploys, monitors and retires AI systems in a way that is aligned with its strategy, risk appetite, legal obligations and safe risk free societal expectations. Modern business leaders are discovering that robust AI governance is not only a defensive shield against fines and scandals; it is also a powerful enabler of innovation, talent attraction, capital access and long-term value creation.

Defining AI Governance in the 2026 Business Context

In 2026, the most advanced organizations treat AI governance as a structured framework that integrates policy, process, technology and culture. It spans the entire AI lifecycle, from problem framing and data acquisition through model development, testing, deployment, monitoring and decommissioning, and it connects these technical activities to the wider corporate systems that govern risk, ethics, compliance and performance.

Leading standards bodies and regulators have converged on similar principles. The OECD has articulated widely adopted AI principles emphasizing human-centered values, fairness, transparency and accountability. The European Union has moved from policy debate to binding rules with the EU AI Act, which classifies AI systems by risk and imposes strict obligations on high-risk applications. In the United States, the White House Office of Science and Technology Policy has set expectations through its Blueprint for an AI Bill of Rights, while regulators such as the U.S. Federal Trade Commission have signaled that deceptive or discriminatory AI practices will be treated as violations of existing consumer protection and competition laws.

For corporate leaders, these developments mean that AI governance must be explicit, documented and auditable. It is no longer sufficient to rely on informal practices or assume that existing IT controls will automatically extend to AI. Directors and C-suite executives are being asked to explain how their organizations identify AI use cases, assess risks, ensure data quality, test for bias, protect privacy, secure models, manage third-party vendors and provide avenues for recourse when AI systems cause harm.

On business-fact.com, the discussion of artificial intelligence in business has increasingly focused on this shift from experimentation to institutionalization. Companies that once celebrated rapid AI pilots now emphasize disciplined deployment, clear accountability and measurable impact, recognizing that AI governance is the bridge between technological possibility and sustainable, trustworthy performance.

Strategic Imperatives: Linking AI Governance to Business Value

For modern business leaders, AI governance is most effective when it is explicitly linked to strategic objectives in revenue growth, cost efficiency, risk management, innovation and market positioning. Organizations that treat governance purely as a constraint often find that AI initiatives stall under the weight of bureaucracy. By contrast, those that integrate governance into their strategy and operating model discover that it accelerates adoption by reducing uncertainty, aligning stakeholders and building trust.

In the capital markets, investors increasingly scrutinize AI practices as part of broader assessments of corporate resilience and environmental, social and governance performance. Major institutional investors and asset managers regularly reference AI-related risks in their stewardship reports and engagements with portfolio companies, and global standard setters such as the International Sustainability Standards Board and IFRS Foundation have expanded their guidance on sustainability and risk disclosure to encompass digital and technology-related risks, including AI. For companies seeking to access equity and debt markets, robust AI governance frameworks are becoming an important signal of maturity and risk awareness, complementing traditional metrics tracked on stock market performance.

Customer expectations are evolving just as rapidly. In sectors such as banking, insurance, healthcare and retail, consumers increasingly ask how their data is used, whether AI systems can explain their decisions and what recourse exists when automated outcomes seem unfair. Research from organizations such as Pew Research Center and World Economic Forum has highlighted growing public concern about AI-driven surveillance, bias and job displacement, reinforcing the need for transparent and responsible practices. Businesses that can credibly demonstrate that their AI systems are designed and governed with fairness, privacy and security in mind are better positioned to differentiate their brands, command premium pricing and maintain customer loyalty in crowded markets.

Internally, AI governance has become a key enabler of transformation in employment and workforce strategy. As organizations adopt AI to automate routine tasks and augment knowledge work, employees across functions-from marketing and finance to operations and HR-seek clarity on how AI will affect roles, performance expectations and career paths. Executive teams that connect AI governance to employment strategy and talent development, rather than treating it solely as a technical or legal issue, are more successful in managing change, reducing resistance and unlocking productivity gains.

Regulatory and Legal Landscape Across Key Markets

By 2026, the regulatory landscape for AI is heterogeneous but rapidly converging around common expectations for transparency, accountability and risk-based controls. Business leaders operating across global markets must therefore navigate a complex mosaic of rules while maintaining a coherent enterprise-wide governance approach.

In the European Union, the EU AI Act has become the most comprehensive AI-specific regulation in force, introducing a risk-based classification of AI systems and imposing strict requirements on high-risk applications in areas such as credit scoring, employment screening, critical infrastructure and healthcare. Organizations deploying such systems must implement robust risk management, data governance, logging, transparency, human oversight and cybersecurity controls, and they face significant penalties for non-compliance. The European Commission provides detailed guidance on the European approach to AI, which has become a reference point for regulators in other regions.

In the United States, sectoral regulators such as the U.S. Securities and Exchange Commission, Federal Reserve, Office of the Comptroller of the Currency and Federal Deposit Insurance Corporation have all issued guidance on the use of AI and machine learning in financial services, emphasizing model risk management, explainability and fair lending practices. The National Institute of Standards and Technology (NIST) has published a widely adopted AI Risk Management Framework, which many organizations in banking, healthcare and critical infrastructure use as a foundation for their internal governance structures.

Across Asia, jurisdictions such as Singapore, Japan, South Korea and China have advanced their own regulatory frameworks. The Monetary Authority of Singapore has developed FEAT principles for AI in finance, focusing on fairness, ethics, accountability and transparency in algorithmic decision-making. Japan's government has aligned its AI strategy with the OECD principles, while South Korea and China have introduced guidelines on algorithmic recommendation, deepfakes and data protection. These developments reflect broader shifts in global economic governance, where AI is now treated as a strategic asset and a potential systemic risk.

For multinational corporations, the challenge is to design AI governance frameworks that are sufficiently flexible to accommodate regional variations while maintaining common standards across the enterprise. Many leading organizations adopt a "highest common denominator" approach, aligning internal policies with the most stringent applicable rules, particularly in high-risk domains such as credit, insurance underwriting, healthcare diagnostics and employment decisions. As with data protection following the introduction of the EU General Data Protection Regulation, companies that proactively align their AI practices with emerging global norms often gain a first-mover advantage and reduce the cost of future compliance.

Building an Effective AI Governance Framework

An effective AI governance framework connects corporate strategy, risk management, technology and culture in a coherent system. On business-fact.com, this is increasingly described as an operating model that spans policy, people, process and platforms, rather than a static document or a set of isolated controls.

At the policy level, organizations define their AI principles, risk appetite and minimum standards. Many draw on external references such as the OECD AI Principles, the NIST AI Risk Management Framework and sector-specific guidance from regulators and industry bodies. These policies typically address topics such as fairness, transparency, human oversight, privacy, security, robustness, sustainability and accountability, and they clarify which AI use cases are prohibited, restricted or prioritized.

From a structural perspective, leading companies establish cross-functional AI governance bodies that include representation from business units, risk, compliance, legal, data science, IT, HR and, in some cases, external advisors. These bodies are responsible for approving high-risk use cases, overseeing model risk management, resolving ethical dilemmas and reporting to the board. In financial institutions, such structures often build on existing model risk committees and align with broader banking governance frameworks, while in technology-led firms they may be integrated with product councils and security review boards.

Process discipline is critical. Mature organizations implement standardized workflows for AI project intake, data sourcing, model development, validation, deployment and monitoring. These workflows include checkpoints for risk assessment, legal review, privacy impact analysis, security testing and ethical evaluation. They also define clear criteria for performance measurement, incident reporting and model retirement. Over time, these processes become embedded in the organization's broader innovation and technology management, enabling AI initiatives to scale without losing control.

Technology platforms play an increasingly important role in operationalizing AI governance. Model registries, experiment tracking systems, automated testing frameworks, bias detection tools and monitoring dashboards allow organizations to enforce policies consistently and generate auditable evidence of compliance. Cloud providers such as Microsoft, Amazon Web Services and Google Cloud have expanded their toolkits to support responsible AI practices, while specialized vendors offer solutions for explainability, robustness testing and model inventory. Business leaders are expected to understand, at a high level, how these platforms support governance and how they integrate with existing risk and compliance systems.

Risk, Ethics and Trust in AI-Driven Business Models

Trust is the central currency of AI adoption in 2026. Without it, customers hesitate to share data, employees resist new tools, regulators scrutinize deployments more aggressively and investors demand higher risk premiums. AI governance is therefore inseparable from the broader agenda of building and maintaining trust in digital business models.

Ethical concerns cut across markets and sectors. Issues such as algorithmic bias, discrimination, opaque decision-making, surveillance and manipulation have become central to public debates in the United States, Europe and Asia. Research from organizations such as MIT and Stanford University has documented cases where AI systems produced biased outcomes in hiring, lending, healthcare and criminal justice, prompting regulators and civil society groups to call for stronger safeguards. Business leaders cannot afford to assume that technical excellence alone will prevent such outcomes; they must actively manage ethical risks through design choices, governance structures and cultural norms.

Transparency and explainability remain challenging, particularly for complex models such as deep neural networks and large language models. Yet regulators, courts and customers increasingly expect organizations to provide meaningful explanations of AI-driven decisions, especially when these decisions affect access to credit, employment, healthcare or essential services. The European Court of Justice and national regulators have signaled that opaque systems may be incompatible with fundamental rights frameworks, while the U.S. Equal Employment Opportunity Commission and Consumer Financial Protection Bureau have clarified that companies remain responsible for discriminatory outcomes even when they rely on third-party AI systems. In this context, explainability is not only a technical property but also a legal and reputational imperative.

Security and resilience have also emerged as core governance concerns. The rise of adversarial attacks, model extraction, data poisoning and prompt injection has demonstrated that AI systems can be manipulated in ways that undermine their reliability and expose organizations to fraud, data breaches and operational disruption. Cybersecurity agencies such as the U.S. Cybersecurity and Infrastructure Security Agency and the UK National Cyber Security Centre have issued guidance on securing AI systems, and boards increasingly expect management to treat AI security as an extension of cyber risk management, with appropriate controls, testing and incident response plans.

For business leaders, the central lesson is that trust in AI cannot be outsourced or delegated solely to technical teams. It must be built into strategy, culture and leadership behavior, and it must be supported by concrete evidence-clear policies, transparent communications, robust controls and credible accountability mechanisms. Organizations that succeed in this regard are better positioned to deploy AI at scale, explore new business models and maintain their license to operate in a rapidly evolving regulatory and social landscape.

AI Governance, Employment and the Future of Work

The impact of AI on employment has shifted from speculative debate to concrete organizational reality. Across the United States, Europe and Asia, companies are using AI to automate tasks in customer service, finance, logistics, marketing, software development and professional services, while simultaneously creating new roles in data science, AI operations, product management and digital risk. For readers of business-fact.com, the central question is no longer whether AI will affect the workforce, but how leaders can manage this transition responsibly and competitively.

AI governance provides the framework for addressing this question. Organizations with mature governance practices integrate workforce considerations into their AI strategies, assessing not only productivity gains and cost reductions but also implications for job design, skills requirements, career progression and organizational culture. They collaborate closely with HR, learning and development and labor representatives to design reskilling programs, update performance management systems and communicate transparently about change. In regions with strong labor protections, such as the European Union, this approach aligns with regulatory expectations for consultation and social dialogue, while in more flexible labor markets it helps maintain engagement and retention in a competitive talent environment.

International organizations such as the International Labour Organization and the World Economic Forum continue to publish research and guidance on the future of work in an AI-driven economy, emphasizing the importance of lifelong learning, social protection and inclusive growth. National governments in countries such as Germany, Singapore and Canada have launched large-scale reskilling initiatives, often in partnership with major employers and educational institutions, to prepare workers for AI-augmented roles. For businesses, active participation in such initiatives is both a social responsibility and a strategic investment in future capability.

On business-fact.com, the interplay between AI, employment trends and founder-led innovation is a recurring theme. Founders and CEOs who communicate a clear vision for how AI will augment rather than simply replace human work are more likely to attract high-caliber talent, secure support from boards and investors and avoid the cultural backlash that can derail transformation programs. AI governance, in this sense, is as much about human capital strategy as it is about technology and regulation.

Implications for Founders, Investors and Financial Institutions

For founders and early-stage companies, AI governance might appear at first glance to be a concern for large incumbents, but by 2026 it has become a decisive factor in scaling and accessing capital. Venture capital firms, growth equity investors and corporate venture arms increasingly assess AI governance practices as part of their due diligence, particularly in regulated sectors such as fintech, healthtech and edtech. Startups that can demonstrate clear policies on data use, model development, security and ethics, along with evidence of implementation, are better positioned to attract investment and form partnerships with larger enterprises.

In the financial sector, AI governance has become deeply intertwined with banking and investment risk management. Banks and asset managers use AI for credit scoring, fraud detection, algorithmic trading, portfolio optimization and customer engagement, but they operate under strict regulatory oversight. Supervisory authorities in the United States, European Union, United Kingdom and Asia have made it clear that the use of AI does not diminish institutions' responsibilities for prudent risk management, fair treatment of customers and market integrity. Model risk management frameworks, originally developed for traditional quantitative models, are being extended to cover machine learning and generative AI, with heightened focus on explainability, validation and ongoing monitoring.

At the same time, AI is reshaping capital markets and the broader global economy. Algorithmic trading and market-making strategies, often powered by advanced AI, influence liquidity and price formation across major exchanges in the United States, Europe and Asia. Regulators such as the U.S. Securities and Exchange Commission and the European Securities and Markets Authority continue to refine their approaches to automated trading and market surveillance, recognizing that AI-driven strategies can amplify both efficiency and systemic risk. For corporate treasurers and CFOs, understanding how AI affects market dynamics is becoming part of the broader toolkit for navigating volatility and optimizing capital structure.

In the crypto and digital asset space, AI governance intersects with debates about market integrity, fraud detection and decentralized finance. While speculative interest in digital assets has fluctuated, serious players in the sector are increasingly focused on robust compliance, transparency and risk management, recognizing that long-term viability depends on trust and regulatory acceptance. For readers of business-fact.com, the convergence of crypto innovation and AI governance presents both opportunities and challenges, particularly as regulators in the United States, Europe and Asia move to clarify rules for tokenized assets, stablecoins and decentralized platforms.

From Compliance to Competitive Advantage

As 2026 progresses, the most forward-looking organizations treat AI governance not as a static set of rules but as a dynamic capability that evolves with technology, regulation and market expectations. They invest in leadership education, cross-functional collaboration and continuous improvement, recognizing that AI governance is a journey rather than a destination.

This evolution is reflected in the way AI is discussed across domains such as technology strategy, marketing and customer engagement, global expansion and sustainable business models. Companies that embed governance into their AI initiatives from the outset are more likely to launch products that meet regulatory expectations, resonate with customers, attract top talent and withstand public scrutiny. They are also better positioned to participate in emerging ecosystems, such as cross-industry data collaborations, AI safety consortia and public-private partnerships focused on societal challenges.

External resources from organizations such as the World Economic Forum, OECD, NIST, European Commission, International Labour Organization and leading academic institutions offer practical guidance and benchmarks for responsible AI. Business leaders who engage with these resources, benchmark their practices against peers and contribute to public dialogues on AI governance help shape the environment in which they operate, rather than simply reacting to it.

For modern business leaders, AI governance has become a defining leadership challenge of this decade. It demands a combination of strategic vision, technical literacy, ethical judgment and stakeholder engagement that few previous technologies have required. Yet for those who rise to this challenge, AI governance offers a pathway to sustainable competitive advantage, resilient operations and enduring trust in an increasingly automated and data-driven world.

As organizations across the United States, Europe, Asia, Africa and South America continue to integrate AI into their core operations, the insights, case studies and analysis shared here daily will remain a valuable resource for executives, founders, investors and policymakers seeking to navigate this complex and rapidly evolving landscape with clarity, responsibility and ambition.
Business Intelligence Metrics That Drive Better Decisions

Last updated by Editorial team at business-fact.com on Wednesday 28 October 2026
Article Image for Business Intelligence Metrics That Drive Better Decisions

Business Intelligence Metrics That Drive Better Decisions

Now business leaders across North America, Europe, Asia and beyond are facing a paradox: they have access to more data than at any time in history, yet it has never been harder to decide what truly matters. In our team this tension is felt daily in conversations with executives, founders and investors who are trying to separate signal from noise. Business intelligence has moved far beyond static dashboards and backward-looking reports; it now sits at the center of strategy, capital allocation, risk management and organizational design. The organizations that win in this environment are those that define, measure and act on a focused set of business intelligence metrics aligned with their strategic intent, while resisting the temptation to track everything.

The Strategic Role of Business Intelligence in 2026

By 2026, business intelligence has become inseparable from corporate strategy. Boards and executive teams no longer treat analytics as a support function; instead, data and metrics form the starting point for discussions about growth, restructuring, digital transformation and entry into new markets. In the United States, United Kingdom, Germany and other advanced economies, regulators, investors and employees increasingly expect leaders to justify decisions with transparent, auditable metrics, whether the topic is pricing, layoffs, sustainability or AI deployment. This expectation is reshaping how companies design their business intelligence environments and which metrics they elevate to board-level visibility.

Modern business intelligence integrates financial performance, operational efficiency, customer behavior, workforce dynamics and external macroeconomic indicators into a cohesive narrative. Rather than relying solely on quarterly financial statements, decision-makers look to real-time dashboards that combine internal data with external benchmarks from sources such as the World Bank and the OECD to understand how their performance compares across regions and sectors. Learn more about the evolving global economy and its implications for data-driven decision-making. In this context, the central challenge is no longer data collection, but metric selection: choosing the handful of indicators that truly drive competitive advantage and long-term value creation.

From Data to Decisions: Defining High-Impact Metrics

High-impact business intelligence metrics share several characteristics that distinguish them from the long lists of indicators that clutter many dashboards. They are directly linked to strategic objectives, are understandable to non-technical stakeholders, can be influenced by management actions within a reasonable timeframe, and are measured consistently across regions and business units. Executives in the United States, Europe and Asia increasingly demand metrics that bridge the gap between operational activity and financial outcomes, enabling them to see how changes in customer experience, digital adoption or supply chain reliability will ultimately affect revenue, margin and cash flow.

On business-fact.com, practitioners emphasize that effective metrics are not static; they evolve as business models, technologies and regulatory environments change. For example, a subscription-based software company in Canada or Germany might initially focus on monthly recurring revenue and churn, but as its artificial intelligence capabilities mature, it may introduce new metrics around AI-driven product usage, personalization quality and model performance, which in turn influence customer lifetime value and expansion revenue. Leaders who understand the interplay between these metrics are better equipped to make trade-offs between short-term profitability and long-term growth. Readers can explore broader perspectives on business strategy and metrics in this context.

Financial and Stock Market Metrics: Beyond Traditional Reporting

Financial metrics remain the backbone of executive decision-making, but in 2026 they are increasingly enriched by market-based indicators and advanced analytics. Traditional measures such as revenue growth, gross margin and operating cash flow are now complemented by forward-looking indicators that incorporate scenario analysis, stress testing and probabilistic forecasting. Public companies in the United States, United Kingdom and Asia-Pacific rely on a combination of internal financial metrics and external signals from stock markets and credit markets to calibrate their capital allocation strategies. Learn more about dynamic stock market intelligence and its role in executive decision-making.

Market capitalization, price-to-earnings ratios and credit spreads remain important, but sophisticated investors and corporate finance teams increasingly examine metrics such as earnings quality, revenue concentration risk, geographic exposure and sensitivity to macroeconomic variables like interest rates and inflation. Resources such as the International Monetary Fund and the Bank for International Settlements provide essential context on global financial conditions that shape these analyses. Companies in sectors as diverse as technology, manufacturing and financial services are also integrating environmental, social and governance indicators into their investor communications, responding to frameworks promoted by organizations such as the IFRS Foundation and the Task Force on Climate-related Financial Disclosures. This integration underscores a broader shift: financial metrics are no longer viewed in isolation, but as the outcome of a complex system of operational, human and environmental drivers.

Operational Excellence and Productivity Intelligence

While financial metrics answer the question of "what happened," operational metrics explain "why it happened" and "what can be improved." In 2026, organizations across Europe, North America and Asia are deploying advanced business intelligence platforms to monitor and optimize their operations in real time. Metrics such as cycle time, throughput, defect rates, on-time delivery and inventory turns have long been staples of operations management, but they are now enriched with sensor data, IoT telemetry and predictive analytics, especially in manufacturing hubs like Germany, Japan and South Korea.

Operational intelligence has become a strategic differentiator for global supply chains that span Asia, Europe, Africa and the Americas. Companies track supplier reliability, logistics lead times, port congestion and geopolitical risk indicators to anticipate disruptions and reconfigure sourcing strategies. Publicly available data from organizations such as the World Trade Organization and UNCTAD provide macro-level insights that complement internal metrics. On business-fact.com, executives frequently note that the most valuable operational metrics are those that connect directly to customer satisfaction and financial outcomes, such as the relationship between delivery reliability in Europe and customer churn in key markets. By linking operational dashboards to strategic KPIs, leaders can prioritize investments in automation, process redesign and workforce upskilling that yield measurable returns.

Customer and Market Intelligence in a Fragmented World

Customer and market intelligence metrics have grown in importance as consumer behavior becomes more fragmented across regions and channels. In the United States, Europe and Asia, companies are using business intelligence to understand not only what customers buy, but why they buy, how they engage and how their preferences evolve over time. Metrics such as net promoter score, customer satisfaction indices, digital engagement depth, conversion rates and customer lifetime value provide a multidimensional view of customer health, but in 2026 they are increasingly augmented by behavioral and sentiment analytics derived from digital interactions.

Marketing leaders are under pressure to demonstrate measurable returns on their budgets, particularly in a macroeconomic environment characterized by slower growth and higher capital costs. They turn to advanced attribution models, media mix modeling and cohort analyses to understand which channels, messages and experiences drive profitable growth. Learn more about data-driven marketing strategies that convert customer intelligence into competitive advantage. External benchmarks from organizations such as McKinsey & Company, Gartner and Forrester help CMOs and CEOs assess whether their metrics are competitive with peers in their sector and region.

The rise of privacy regulations in the European Union, United Kingdom and other jurisdictions has also reshaped customer intelligence metrics. Companies now track consent rates, data quality scores and privacy incident metrics as part of their core dashboards, recognizing that trust is a critical asset. Independent guidance from bodies such as the European Data Protection Board and national regulators informs how organizations design consent journeys and data governance frameworks, which in turn influence the scope and reliability of customer analytics.

Workforce, Employment and Human Capital Metrics

The period from 2020 to 2026 has transformed how organizations think about work, talent and productivity. Hybrid and remote models, skills shortages in technology and AI, and shifting employee expectations in markets from the United States and Canada to Germany, India and Singapore have forced leaders to adopt a more sophisticated approach to workforce metrics. Traditional indicators such as headcount, turnover and absenteeism are no longer sufficient; organizations are now tracking engagement scores, internal mobility rates, skills inventories, diversity metrics and time-to-productivity for new hires in order to make informed decisions about hiring, reskilling and organizational design.

On business-fact.com, readers exploring employment and workforce trends increasingly look for metrics that link human capital to business performance. Research from institutions such as the World Economic Forum and the International Labour Organization underscores the economic value of skills development, inclusive workplaces and employee well-being. Companies in Europe, North America and Asia are building internal skills taxonomies and using AI-driven tools to map current capabilities against future needs, enabling them to quantify skills gaps and prioritize training investments. Metrics such as training hours per employee, certification completion rates and internal fill rates for critical roles are gaining prominence at board level as leading indicators of future competitiveness.

At the same time, regulators and investors in markets such as the United Kingdom and the European Union are demanding greater transparency on workforce metrics, including pay equity, health and safety, and collective bargaining coverage. This trend is pushing organizations to standardize their human capital reporting and integrate it into their broader business intelligence frameworks, recognizing that human capital is as important to enterprise value as financial and physical capital.

AI-Driven Business Intelligence and Advanced Analytics

Artificial intelligence has moved from experimental projects to core infrastructure in business intelligence by 2026. Organizations in the United States, Europe, China, Singapore and beyond are using AI to automate data integration, generate forecasts, detect anomalies and even propose decisions. Predictive and prescriptive analytics are now embedded in many leading platforms, enabling companies to move from descriptive reporting to proactive decision-support. Executives interested in the intersection of artificial intelligence and business increasingly focus on the metrics that govern AI performance, risk and value creation.

AI-driven metrics extend beyond traditional business indicators to include model accuracy, drift, bias measurements, data lineage and explainability scores. These metrics are essential for ensuring that AI-driven recommendations are reliable, fair and compliant with emerging regulations such as the EU AI Act. Organizations such as NIST and the OECD provide frameworks and guidelines for trustworthy AI that influence how companies in North America, Europe and Asia design their AI governance metrics. Decision-makers are learning that without robust AI performance and risk metrics, the apparent precision of AI-generated forecasts can be misleading and potentially harmful.

At the same time, AI is transforming how metrics themselves are consumed. Natural language interfaces and conversational analytics allow executives to query complex datasets in plain language, asking questions such as "How did our customer acquisition cost in Germany change after the pricing adjustment in Q2?" and receiving instant, contextualized answers. This development lowers the barrier to data-driven decision-making across the organization, but it also demands rigorous data governance and metric definitions to avoid confusion and misinterpretation. Readers can explore the broader landscape of technology-driven transformation and its implications for business intelligence on business-fact.com.

Innovation, Founders and Investment Metrics

In innovation-driven economies from the United States and Canada to Germany, Sweden and Singapore, founders and investors rely on a distinct set of business intelligence metrics to evaluate opportunities, manage portfolios and allocate capital. Traditional financial statements provide an incomplete picture of early-stage ventures, so metrics such as monthly recurring revenue, burn rate, runway, customer acquisition cost, payback period and cohort retention have become central to founder and investor discussions. On business-fact.com, readers interested in founders and entrepreneurial journeys increasingly look for guidance on how to define and interpret these metrics across different sectors and geographies.

Venture capital and private equity firms in North America, Europe and Asia are also adopting more sophisticated portfolio-level metrics, including value creation scorecards, operational improvement indices and ESG performance measures. Organizations such as PitchBook and CB Insights provide market-wide data that allows investors to benchmark their portfolios against global trends in valuation, exit activity and sector performance. Learn more about the evolving landscape of investment intelligence and how metrics are reshaping capital allocation decisions.

Innovation metrics extend beyond financial and customer indicators to capture the health of the innovation pipeline itself. Companies track R&D intensity, patent filings, time-to-prototype, experimentation velocity and the percentage of revenue derived from products launched in the last three to five years. These metrics are particularly important in technology-intensive sectors in the United States, Germany, Japan and South Korea, where the pace of change demands continuous renewal. External benchmarks from organizations such as the World Intellectual Property Organization and the OECD provide comparative data on innovation performance by country and sector, enabling leaders to position their efforts in a global context.

Banking, Fintech, Crypto and Financial Data Intelligence

In banking and financial services, business intelligence metrics have become mission-critical as institutions navigate regulatory scrutiny, digital disruption and the rise of fintech and crypto-assets. Traditional banking metrics such as net interest margin, cost-to-income ratio, non-performing loan ratios and liquidity coverage are now integrated with digital adoption indicators, fraud detection metrics and customer experience scores. Readers can explore sector-specific insights on banking and financial transformation and how metrics are reshaping strategies in the United States, Europe and Asia-Pacific.

Fintech firms and digital banks, particularly in markets such as the United States, United Kingdom, Singapore and Brazil, rely on granular, real-time metrics to manage growth, risk and unit economics. They track onboarding completion rates, verification success, transaction frequency, interchange revenue and fraud loss ratios, often leveraging AI-driven anomaly detection to identify emerging risks. Regulatory bodies such as the European Banking Authority, the Federal Reserve and the Monetary Authority of Singapore increasingly expect institutions to demonstrate robust data governance and risk metrics, particularly in areas such as model risk management and operational resilience.

Crypto-asset markets add another layer of complexity. While the sector remains volatile, institutional investors and corporates are paying closer attention to on-chain metrics, liquidity indicators and regulatory developments. On business-fact.com, readers seeking to understand crypto's evolving role in finance are encouraged to consider not only price movements but also metrics such as network activity, stablecoin flows and regulatory clarity across jurisdictions. Institutions such as the Financial Stability Board and the Bank for International Settlements provide analytical reports that help contextualize the systemic implications of digital assets and guide risk metrics for banks and asset managers.

Sustainability, ESG and Long-Term Value Metrics

Sustainability and ESG metrics have moved from the periphery to the core of business intelligence in 2026, particularly in Europe, the United Kingdom and increasingly in North America and Asia-Pacific. Investors, regulators and customers expect companies to report on their environmental impact, social responsibility and governance practices with the same rigor as financial results. Metrics such as greenhouse gas emissions, energy intensity, water usage, waste reduction, gender and ethnic diversity, human rights practices and board independence are now integrated into mainstream dashboards. Learn more about sustainable business practices and how they intersect with financial performance.

Frameworks developed by organizations such as the Global Reporting Initiative, the Sustainability Accounting Standards Board and the CDP provide guidance on which metrics are most material for different industries and regions. Companies operating across Europe, Asia, Africa and the Americas must also navigate regulatory requirements such as the EU's Corporate Sustainability Reporting Directive, which mandates detailed ESG disclosures. Independent initiatives like the Science Based Targets initiative help organizations set and track emissions reduction goals aligned with global climate objectives, while the UN Global Compact offers principles for responsible business conduct.

For decision-makers, the key challenge is to integrate ESG metrics into core business intelligence rather than treating them as a separate reporting exercise. Leading companies are building causal models that link sustainability metrics to financial outcomes, such as the impact of energy efficiency on operating costs, the relationship between diversity and innovation performance, or the effect of supply chain transparency on brand value. This integrated approach enables executives to make trade-offs and investments based on a holistic view of long-term value creation.

Building a Trusted, Global Business Intelligence Foundation

Underlying all of these metrics is the critical question of trust. In 2026, organizations that operate across North America, Europe, Asia, Africa and South America must ensure that their data and metrics are accurate, consistent and ethically sourced. Data governance frameworks, standardized definitions and clear ownership structures are essential for maintaining confidence in business intelligence systems. Online here leaders exploring cross-border business dynamics consistently highlight the importance of harmonized metrics when comparing performance across regions, business units and time periods.

Independent standards and best practices from organizations such as ISO, COSO and ISACA provide guidance on information governance, internal controls and assurance over data and analytics systems. Companies are increasingly subjecting their key metrics and underlying data processes to internal audit and external assurance, recognizing that investors, regulators and employees base critical decisions on these figures. Public institutions such as Eurostat, Statistics Canada and the U.S. Bureau of Labor Statistics also serve as benchmarks for macroeconomic and labor market data, enabling organizations to situate their performance within broader national and regional trends.

For business leaders, the path forward involves more than technology investment. It requires a deliberate, strategic approach to selecting metrics that reflect the organization's purpose, business model and risk appetite, combined with a culture that values evidence-based decision-making and transparency. As business-fact.com continues to track developments across business and markets, it is clear that the organizations that thrive in 2026 and beyond will be those that treat business intelligence metrics not as a reporting obligation, but as a strategic asset that shapes every significant decision they make.

Why Capital Efficiency Matters for Growing Businesses

Last updated by Editorial team at business-fact.com on Tuesday 27 October 2026
Article Image for Why Capital Efficiency Matters for Growing Businesses

Why Capital Efficiency Matters for Growing Businesses in 2026

Capital Efficiency as the Defining Discipline of Modern Growth!

Capital efficiency really has moved from being a specialist financial concept to a defining discipline for ambitious companies seeking sustainable scale. In an environment shaped by higher interest rates, volatile equity markets, shifting geopolitical risks and rapid technological disruption, the ability to turn every unit of capital into outsized and durable value has become a central determinant of which businesses endure and which quietly disappear. For people here, who follow events across business and strategy, stock markets, employment trends, founder stories and the global economy, capital efficiency is not an abstract metric; it is the connecting thread between growth, resilience and long-term value creation.

Capital efficiency, in its most practical sense, describes how effectively a company converts financial resources-equity, debt, retained earnings and working capital-into revenue, profit, cash flow and strategic advantage. It is expressed through ratios such as return on invested capital, cash conversion, payback periods and unit economics, but behind the numbers lies a deeper management philosophy: disciplined allocation, clear prioritization, rigorous measurement and a willingness to say no to attractive but non-essential initiatives. As global investors, regulators and customers demand greater transparency and accountability, capital efficiency has become a powerful signal of managerial competence and organizational maturity across markets from the United States and Europe to Asia, Africa and Latin America.

From "Growth at All Costs" to "Efficient Growth"

The years following the global financial crisis and, later, the pandemic-era liquidity wave fostered a decade in which many technology and high-growth companies embraced "growth at all costs," fuelled by abundant venture capital, low interest rates and a belief that scale would inevitably yield profitability. That era has ended. Central banks such as the U.S. Federal Reserve and the European Central Bank have normalized interest rates, public market investors have repriced risk, and private capital has become more selective. As analysis from institutions like the Bank for International Settlements shows, the cost of capital has structurally risen, forcing management teams to reassess how they deploy every dollar, euro or yen.

Public equity markets in the United States, United Kingdom, Germany and across Asia have increasingly rewarded companies that deliver efficient growth-measured by strong free cash flow margins, disciplined operating expense trajectories and credible paths to profitability-while applying a discount to businesses that rely on perpetual external financing to sustain expansion. Investors now examine metrics such as rule-of-40 scores for software companies, cash burn multiples and revenue efficiency ratios with far greater scrutiny than in previous cycles. Readers tracking stock market developments on business-fact.com will recognize how this shift has reshaped valuations in technology, consumer, industrials and financial services alike.

This pivot has been especially visible in innovation hubs such as the United States, the United Kingdom, Germany, Canada, Singapore and Israel, where venture and growth equity investors have reoriented term sheets and portfolio expectations around capital-efficient scaling. Reports from organizations like McKinsey & Company and Bain & Company have highlighted that top-quartile performers in many sectors are not necessarily those with the fastest top-line growth, but those that combine moderate to strong growth with superior returns on invested capital and consistent cash generation. Learn more about how leading management consultancies view the link between capital allocation and performance at McKinsey's corporate finance insights.

The Strategic Logic of Capital Efficiency

For growing businesses, capital efficiency matters because it enhances strategic optionality, resilience and bargaining power. A company that can self-fund a substantial portion of its growth through internally generated cash flows is less dependent on external investors and lenders, less exposed to market cycles and more capable of investing counter-cyclically when competitors are constrained. This dynamic has been observable across industries, from software and financial technology to advanced manufacturing and consumer brands, in markets such as North America, Europe and Asia-Pacific.

Efficient capital deployment allows management teams to prioritize initiatives that deliver the highest risk-adjusted returns, whether that means investing in automation, expanding into new geographies, acquiring complementary businesses or accelerating product development. By continuously measuring returns on projects and reallocating capital away from underperforming activities, companies can compound value over time in a manner that is difficult for less disciplined rivals to match. The Harvard Business Review has repeatedly emphasized that superior capital allocation is one of the few enduring sources of competitive advantage in mature industries; readers can explore this perspective further through Harvard Business Review's strategy and finance articles.

Capital efficiency also strengthens a company's position in negotiations with investors, banks, suppliers and strategic partners. When a business demonstrates strong unit economics, prudent leverage and consistent cash generation, it can access more favorable terms from lenders, attract long-term shareholders rather than speculative capital and negotiate from a position of strength with suppliers and distributors. This is particularly relevant in banking relationships, where institutions such as JPMorgan Chase, HSBC, Deutsche Bank and leading regional banks in Asia and Latin America increasingly rely on rigorous risk models and regulatory capital requirements that reward borrowers with robust financial profiles. Readers focusing on banking dynamics will recognize how capital-efficient borrowers are better positioned to navigate tightening credit standards.

Measuring Capital Efficiency in Practice

While the concept of capital efficiency is broad, growing businesses typically focus on a set of practical, decision-oriented metrics. Return on invested capital (ROIC) remains central, as it compares operating profits after taxes with the total capital employed in the business, providing a clear view of whether a company is truly creating value above its cost of capital. Organizations such as MSCI and S&P Global incorporate ROIC and related measures into their equity research and index methodologies, reinforcing their importance for public and private companies alike. Investors can explore how these metrics influence index construction by reviewing S&P Global's insights on corporate performance.

For high-growth and technology-driven companies, unit economics and payback periods have become critical. Customer acquisition cost, lifetime value, gross margin and payback on sales and marketing spend provide a granular view of whether each incremental customer or cohort is driving profitable growth. Leading venture firms and accelerators across the United States, Europe and Asia have emphasized these metrics as gating criteria for follow-on funding, and platforms such as Y Combinator and Techstars have made capital-efficient growth a core theme in their guidance to founders. Readers interested in how startup ecosystems are evolving can learn more from Y Combinator's startup library.

Cash conversion and working capital efficiency represent another dimension. The speed at which a business converts earnings into cash-via disciplined receivables management, optimized inventory and negotiated payables terms-can determine whether it can fund expansion internally or must rely on external financing. In sectors such as manufacturing, retail, logistics and healthcare across Europe, Asia and the Americas, leaders have embraced advanced analytics and supply chain technologies to improve working capital cycles, often drawing on frameworks from organizations like APICS and research published by the World Bank. Those seeking a macro view of how working capital influences productivity and growth can consult World Bank's enterprise surveys and finance research.

On business-fact.com, capital efficiency is increasingly discussed as a cross-cutting theme in areas such as investment strategy, employment models and innovation management. By linking financial metrics to strategic narratives, the platform highlights how leaders in the United States, Europe, Asia and beyond are integrating financial discipline into their broader growth agendas.

Capital Efficiency and the Founder's Journey

For founders and entrepreneurial teams, capital efficiency is both a mindset and a survival strategy. In the early stages, when access to institutional capital may be limited, the ability to stretch every round of funding, prioritize the most impactful product features and validate market demand with minimal spend can determine whether a venture reaches product-market fit before resources run out. This is as true in Silicon Valley and London as it is in Berlin, Singapore, São Paulo, Nairobi and Bangalore.

Capital-efficient founders tend to design their organizations and operating models with frugality and focus from the outset. They adopt lean experimentation, minimize fixed costs, leverage cloud-based infrastructure, outsource non-core functions and carefully manage hiring. Platforms such as Stripe, Amazon Web Services and Microsoft Azure have lowered the cost of building and scaling digital products, but founders who treat this as an invitation to unbounded experimentation often discover that cloud and tooling expenses can erode margins quickly. In contrast, founders who treat these platforms as tools to accelerate validated bets, rather than to fund endless exploration, are better positioned to maintain healthy unit economics. Learn more about how modern cloud platforms support capital-efficient scaling by reviewing AWS's startup resources.

As ventures grow and attract institutional investors, capital efficiency becomes a crucial element of governance and boardroom dialogue. Experienced investors from firms such as Sequoia Capital, Index Ventures, Accel and leading regional funds in Europe, Asia and Latin America have increasingly emphasized efficient growth in their public letters and investment theses. They encourage founders to build financial planning and analysis capabilities earlier, adopt rolling forecasts and scenario planning and treat capital as a scarce resource even when balance sheets appear strong. Readers interested in founder perspectives on capital discipline can explore Sequoia's "Building Enduring Companies" resources.

On business-fact.com, the founders section frequently highlights case studies where disciplined capital allocation has allowed entrepreneurs to navigate downturns, pivot business models or seize acquisition opportunities. By connecting these narratives to broader news and global trends, the platform underscores that capital efficiency is not merely a financial virtue but a core component of entrepreneurial resilience in markets from North America and Europe to Africa and South America.

The Role of Technology and Artificial Intelligence in Enhancing Capital Efficiency

Technology, and particularly artificial intelligence, has become a powerful enabler of capital efficiency for growing businesses. Where previous generations of managers relied on static spreadsheets and periodic financial reports, today's leaders can harness real-time data, predictive analytics and machine learning to optimize pricing, demand forecasting, inventory, staffing and capital allocation decisions. This transformation is reshaping operating models in sectors as diverse as retail, logistics, manufacturing, financial services and healthcare across the United States, Europe, Asia and beyond.

Modern enterprise resource planning and financial planning platforms, offered by organizations such as SAP, Oracle, Workday and Intuit, integrate operational and financial data to give management teams a dynamic view of performance. When combined with AI-driven analytics from providers like Snowflake, Databricks and Google Cloud, companies can simulate the impact of investment decisions, model different economic scenarios and identify where capital is being underutilized. Executives seeking to understand how data platforms contribute to better financial decisions can explore Snowflake's resources on data-driven finance.

Artificial intelligence is also changing how businesses manage working capital and risk. In banking and payments, for example, machine learning models are used to assess creditworthiness, detect fraud and optimize collections, allowing lenders and merchants to extend credit more confidently while reducing losses. Organizations such as Visa, Mastercard and leading digital banks in Europe and Asia are deploying AI to refine risk models, which in turn influences the availability and pricing of capital for small and mid-sized businesses. Readers interested in the intersection of AI and finance can review Visa's perspectives on AI in payments.

For the audience of business-fact.com, the convergence of technology, artificial intelligence and finance is especially significant. As the platform's coverage illustrates, AI is enabling companies in regions from North America and Europe to Asia-Pacific and Africa to achieve levels of capital efficiency that would have been difficult a decade ago, from predictive maintenance in manufacturing that reduces capital expenditure to algorithmic inventory management in retail that frees up working capital. However, the same technologies can also lead to over-investment if adopted without a clear value hypothesis and robust measurement, reinforcing the need for disciplined capital allocation even in the era of intelligent automation.

Capital Efficiency Across Sectors and Regions

Although the principles of capital efficiency are universal, their application varies by sector and geography. In capital-intensive industries such as energy, infrastructure, automotive and heavy manufacturing, particularly in countries like Germany, Japan, South Korea, China and the United States, efficient deployment of large, long-lived assets is central to competitiveness. Companies in these sectors rely on sophisticated project finance structures, long-term planning and partnerships with governments and financial institutions. Organizations such as the International Energy Agency provide detailed analysis of how capital allocation in energy transitions affects long-term returns and climate objectives; interested readers can explore this further through IEA's investment reports.

In services and digital sectors, including software, media, professional services and fintech, the focus often shifts to human capital, intellectual property and platform economics. Here, capital efficiency is closely tied to how businesses structure pricing, manage customer acquisition, scale platforms and maintain product quality without allowing overhead to balloon. Global technology leaders in the United States, Europe and Asia have demonstrated that disciplined investment in research and development, combined with careful management of go-to-market spending, can yield high-margin, capital-light business models. The OECD provides comparative data on R&D intensity and productivity across advanced and emerging economies, which can be explored at OECD's science, technology and innovation portal.

Regional differences in financial markets and regulatory environments also shape how capital efficiency is pursued. In the United States and the United Kingdom, deep capital markets and active private equity sectors create strong pressures for companies to demonstrate efficient capital allocation as a condition for access to funding. In continental Europe, with its strong bank-based financing traditions and industrial heritage, businesses often focus on balance sheet strength and long-term asset productivity. In Asia, where growth opportunities remain significant in markets such as India, Southeast Asia and parts of China, companies must balance aggressive expansion with the need to maintain healthy leverage and cash flow.

For people tracking global business trends, these regional nuances highlight that capital efficiency is not a one-size-fits-all formula; it is a strategic lens that must be adapted to local conditions, sector dynamics and organizational culture while adhering to universal principles of discipline, transparency and accountability.

Capital Efficiency, Employment and Organizational Design

Capital efficiency inevitably influences how companies structure their workforces and design their organizations. In an era of automation, remote work and global talent markets, management teams must carefully evaluate how investments in people, technology and processes contribute to long-term value creation. This has direct implications for employment patterns in countries such as the United States, the United Kingdom, Germany, India, Brazil and South Africa, as well as across Europe, Asia and Africa more broadly.

Organizations that prioritize capital efficiency do not simply seek to reduce headcount; rather, they aim to align workforce investments with strategic priorities, ensuring that each role contributes meaningfully to revenue growth, customer satisfaction, product innovation or operational excellence. This often involves investing in higher-skilled roles, training and automation tools that enhance productivity, while phasing out activities that can be standardized or outsourced. Institutions such as the World Economic Forum have documented how technology and new business models are reshaping jobs and skills requirements globally; readers can deepen their understanding by visiting WEF's Future of Jobs reports.

From the perspective of employment reporting, capital efficiency is a critical lens through which to interpret restructuring announcements, hiring freezes, automation investments and remote-work strategies. When companies in North America, Europe or Asia announce workforce changes, the underlying driver is often an effort to realign cost structures and capital deployment with evolving market realities. The businesses that manage this transition most successfully are those that communicate transparently, invest in reskilling and maintain a clear narrative about how efficiency gains will support innovation, growth and long-term job creation.

Capital Efficiency, Sustainability and Long-Term Value

Sustainability and capital efficiency are increasingly intertwined. Environmental, social and governance (ESG) considerations, once treated as a separate domain, are now integral to how investors and regulators assess the quality of a company's capital allocation decisions. Investments in energy efficiency, circular economy models, low-carbon technologies and responsible supply chains can enhance long-term returns by reducing operating costs, mitigating regulatory and reputational risks and opening new markets. At the same time, poorly conceived sustainability projects that lack clear financial logic can erode capital efficiency and undermine confidence.

Global frameworks such as those promoted by the Task Force on Climate-Related Financial Disclosures and the International Sustainability Standards Board are pushing companies to provide more detailed information on how climate and sustainability considerations influence strategy and capital expenditure. Asset managers like BlackRock and Vanguard have repeatedly emphasized that sustainable business practices are a prerequisite for long-term value creation. Executives seeking to understand how leading investors integrate ESG and capital allocation can review BlackRock's stewardship and sustainability materials.

For the audience here now, the intersection of sustainable business models and capital efficiency is central to evaluating which companies are genuinely positioned for long-term success. Learn more about sustainable business practices through the work of organizations such as the UN Global Compact and the World Business Council for Sustainable Development, whose insights are accessible via UN Global Compact's resources.

Implications for Investors, Executives and Policymakers

The growing importance of capital efficiency has significant implications not only for corporate leaders but also for investors and policymakers worldwide. For institutional and individual investors, the ability to assess capital allocation quality has become a critical component of portfolio construction and risk management. This involves analyzing ROIC, free cash flow, leverage, dividend and buyback policies, acquisition track records and management's willingness to exit underperforming businesses. Organizations such as the CFA Institute offer frameworks and education on these topics, which can be explored at CFA Institute's investor resources.

Executives, particularly in mid-sized and fast-growing companies, must build internal capabilities that support capital-efficient decision-making. This includes strengthening financial planning and analysis, embedding scenario planning, integrating operational and financial data and fostering a culture where teams understand the cost of capital and the importance of returns. Coverage across investment, marketing, innovation and technology repeatedly illustrates that capital efficiency is not solely the responsibility of finance teams; it is a shared discipline across product, sales, operations and corporate development.

Policymakers and regulators, meanwhile, influence capital efficiency through tax regimes, financial market regulations, competition policy and support for innovation ecosystems. Well-designed policies can encourage productive investment in infrastructure, research and development and human capital, while discouraging speculative or extractive behaviors that undermine long-term growth. Institutions such as the International Monetary Fund and the OECD regularly analyze how policy frameworks shape investment and productivity, and policymakers can access comparative studies through IMF's fiscal and investment research.

Capital Efficiency as a Core Theme for the Next Decade

As time unfolds, it is increasingly clear that capital efficiency will remain a core theme for the coming decade, shaping how businesses in the United States, Europe, Asia, Africa and the Americas grow, compete and create value. The combination of higher capital costs, technological disruption, demographic shifts and sustainability imperatives will continue to reward companies that treat capital as a strategic resource rather than a commodity.

For online fans, this theme cuts across every area of interest-from business strategy and global markets to founders' journeys, employment dynamics and innovation. By focusing on experience, expertise, authoritativeness and trustworthiness in its analysis, the platform aims to equip decision-makers with the insights needed to build organizations that are not only bigger, but better: more disciplined, more resilient and more capable of turning scarce capital into enduring impact.

In an era where uncertainty is the norm rather than the exception, capital efficiency is emerging as one of the few controllable levers that leaders can pull to shape their company's destiny. Those who master it-across industries, regions and stages of growth-are likely to define the next generation of business success stories featured on business-fact.com and across the global business landscape.

Enterprise Automation Beyond Cost Reduction

Last updated by Editorial team at business-fact.com on Monday 26 October 2026
Article Image for Enterprise Automation Beyond Cost Reduction

Enterprise Automation Beyond Cost Reduction: Mega Value in 2026

Automation's New Strategic Role in the Enterprise

By 2026, enterprise automation has moved decisively beyond its early reputation as a blunt instrument for headcount reduction and narrow efficiency gains. Across major markets in North America, Europe and Asia, large and mid-sized organizations are now re-framing automation as a foundational capability for resilience, growth, innovation and risk management, rather than a single-purpose tool for cutting operational expenses. For the audience of business-fact.com, this shift is particularly relevant, because it reshapes how leaders should think about business models, capital allocation, talent strategy and competitive positioning over the next decade.

The evolution has been driven by several converging forces. The maturation of cloud-native platforms, the rapid advances in artificial intelligence, especially generative models, and the normalization of hybrid work have created an environment in which automation can be applied across front, middle and back offices, integrating data, decisions and execution in ways that were not technically or economically feasible even five years ago. At the same time, investors, regulators and customers in the United States, the European Union, the United Kingdom and key Asia-Pacific markets such as Japan, Singapore and Australia are demanding higher levels of transparency, responsiveness and sustainability, expectations that manual processes alone can no longer satisfy.

As a result, leading enterprises are rethinking automation not as an isolated IT initiative, but as a core pillar of their overall business strategy, closely linked to product design, customer experience, workforce development and corporate governance. This more holistic view is changing how boards and executive teams define value, measure returns and structure accountability for automation programs.

From Cost Cutting to Value Creation

The first wave of large-scale automation, dominated by robotic process automation and workflow tools, was mainly justified through labor arbitrage and short payback periods. Organizations in banking, insurance and shared services often built business cases around full-time equivalent reduction, and success was measured by the number of hours "returned to the business." While these gains were real, this narrow framing created a ceiling on strategic impact and, in many cases, generated cultural resistance, as employees perceived automation as a direct threat to job security rather than an enabler of higher-value work.

By 2026, more sophisticated enterprises in sectors ranging from financial services and healthcare to manufacturing, logistics and retail have recognized that the real value of automation lies in its ability to unlock new revenue streams, support differentiated customer experiences, and enable more agile responses to volatile market conditions. For example, leading banks in the United States, the United Kingdom and Singapore are using automation to orchestrate end-to-end onboarding journeys, integrate real-time risk scoring, and personalize offers at scale, which contributes not only to lower operating costs but also to higher customer lifetime value and improved regulatory compliance. Readers interested in how this trend is transforming financial institutions can explore more on modern banking transformations.

External research from organizations such as McKinsey & Company and Boston Consulting Group has highlighted that the majority of value from digital and automation initiatives is now realized through revenue uplift, reduced time-to-market and improved quality, rather than pure cost savings. Learn more about how large-scale digital programs create value by reviewing perspectives from McKinsey on digital transformation. Similarly, the World Economic Forum has emphasized that automation is a central driver of what it terms the "augmented workforce," where human skills such as creativity, empathy and complex problem solving are amplified by intelligent systems, rather than replaced, a vision that can be explored further through the Forum's insights on the future of work.

For business leaders, this reorientation demands new metrics and governance structures. Instead of focusing automation scorecards solely on cost per transaction or cycle-time reductions, progressive organizations are incorporating measures related to customer satisfaction, net promoter scores, cross-sell and up-sell rates, and even environmental performance. This broader lens aligns closely with the multi-dimensional interests of the business-fact.com audience, which spans stock markets, employment, founders and economy-wide impacts.

Automation as a Catalyst for Business Model Innovation

One of the most significant, yet often underappreciated, consequences of enterprise automation is its role in enabling new business models. When processes become programmable, data-rich and consistently executed, organizations gain the ability to experiment with new value propositions, pricing structures and ecosystem partnerships at far lower marginal cost and risk.

In manufacturing and industrial sectors across Germany, Japan and South Korea, automation is underpinning the shift from one-time product sales to "as-a-service" models, in which customers pay for uptime, performance or outcomes rather than physical assets. By integrating sensor data, predictive maintenance algorithms and automated billing workflows, companies can offer highly responsive service-level agreements while maintaining profitability. The World Economic Forum and Siemens have both illustrated how such models depend on end-to-end automation and data integration; readers can deepen their understanding by exploring the WEF's work on Industry 4.0.

In the digital economy, Microsoft, Amazon Web Services and Google Cloud have demonstrated how automation at massive scale allows for dynamic pricing, real-time capacity allocation and continuous deployment of new features, fundamentally changing how software and infrastructure are bought and sold. Learn more about the cloud-native operating model through resources such as Google Cloud's automation and DevOps practices. For founders and investors following business-fact.com, these examples illustrate that automation is not simply an efficiency tool but a precondition for scalable, data-driven business models, especially in highly regulated or capital-intensive industries.

In financial services, automation is enabling embedded finance and "banking-as-a-service," where non-financial brands integrate payment, lending or insurance capabilities directly into their customer journeys. This requires automated onboarding, risk assessment, compliance checks and transaction monitoring that operate reliably at scale. Those tracking developments in this space may find it helpful to review Bank for International Settlements analyses of digital innovation in banking, which provide a regulatory and macroeconomic perspective on how automation is reshaping financial intermediation.

Strengthening Resilience and Operational Risk Management

The pandemic years and subsequent geopolitical tensions, including supply chain disruptions affecting Europe, Asia and North America, exposed the fragility of many enterprise operating models that relied heavily on manual processes, localized expertise and static planning assumptions. In response, executives and boards have elevated resilience and operational risk management to strategic priorities, and automation has become a central lever in achieving these goals.

Automated monitoring, alerting and remediation systems allow organizations to detect anomalies in real time, whether they relate to cyber threats, transaction fraud, supply chain bottlenecks or system outages. IBM, Palo Alto Networks and CrowdStrike have shown how security operations centers can use automation to triage incidents, enrich data with threat intelligence and execute containment actions, significantly reducing mean time to response. For a deeper technical and governance perspective, readers may consult NIST guidance on cybersecurity and automation, which is increasingly referenced by regulators and boards in the United States and beyond.

In banking and capital markets, regulatory expectations from bodies such as the European Central Bank, the Bank of England and the Federal Reserve have pushed institutions to adopt automated controls, real-time reporting and advanced analytics for anti-money laundering, market abuse detection and prudential risk management. This is reshaping how compliance and risk functions operate, moving from periodic, sample-based reviews to continuous, data-driven oversight. Those following developments in this domain can explore more through the Financial Stability Board's work on suptech and regtech, which highlights the role of automation in regulatory technology.

Supply chain resilience is another area where automation delivers benefits far beyond cost reduction. Manufacturers and retailers across the United States, Europe and Asia-Pacific are deploying automated demand forecasting, inventory optimization and logistics orchestration tools that integrate data from suppliers, logistics providers and market signals. MIT Center for Transportation & Logistics provides insights into how these capabilities contribute to more robust global supply chains, which can be explored through its research on supply chain resilience. For readers of business-fact.com, these developments tie directly into broader global business dynamics and the ongoing reconfiguration of trade relationships.

Elevating Customer and Employee Experience

While automation is often associated with back-office processes, its impact on customer and employee experience has become a central differentiator in competitive markets. In banking, telecommunications, retail and travel, customers now expect seamless, omnichannel interactions that are personalized, responsive and consistent across touchpoints. Automation, combined with advanced analytics and AI, makes it possible to orchestrate these experiences at scale while maintaining compliance and quality.

For example, financial institutions in Canada, the Netherlands and Singapore are using AI-powered virtual assistants integrated with automated workflows to handle routine inquiries, initiate transactions and guide customers through complex processes such as mortgage applications or investment onboarding. This not only reduces call center volumes but also shortens time-to-resolution and improves satisfaction. To understand how such capabilities are being deployed responsibly, business leaders can review OECD guidance on AI in finance, which emphasizes the importance of transparency, fairness and accountability.

Employee experience is equally important. Organizations that simply use automation to drive headcount reductions often see morale decline and institutional knowledge erode. In contrast, enterprises that involve employees in identifying automation opportunities, redesign roles to focus on higher-value tasks, and invest in upskilling are more likely to capture sustainable benefits. Deloitte and PwC have documented how "citizen development" programs, where business users build and maintain low-code automations under appropriate governance, can increase engagement and innovation. Learn more about such workforce strategies through Deloitte Insights on the future of work and automation.

This focus on human-centric automation aligns closely with the business-fact.com audience's interest in employment trends and the evolving relationship between technology and labor markets. It also underscores why leading enterprises in regions such as the Nordics, Germany and Japan, which traditionally emphasize social partnership and long-term workforce development, are often at the forefront of responsible automation practices.

Automation, Data and the AI-Driven Enterprise

In 2026, automation cannot be separated from the broader trajectory of artificial intelligence and data strategy. The most advanced organizations are moving toward what analysts and technology providers describe as "AI-driven enterprises," in which data flows seamlessly across functions, and AI models are embedded into decision-making and execution processes through automation platforms. For readers of business-fact.com, this convergence is central to understanding how technology and AI are reshaping competitive advantage.

Generative AI has accelerated this trend by lowering the barrier to designing, documenting and optimizing automated workflows. Tools from providers such as OpenAI, Anthropic and Microsoft can now interpret natural language descriptions of processes, generate automation scripts, propose optimizations and even create test cases and documentation. To explore the broader implications of these technologies, executives may consult resources such as the Stanford HAI reports on the state of AI, which provide a balanced, data-driven overview of global progress and challenges.

However, realizing the full potential of AI-enabled automation requires robust data governance, security and ethical frameworks. The European Union's AI Act, regulatory guidance from authorities in the United States, the United Kingdom and Singapore, and voluntary frameworks from organizations such as ISO and IEEE are shaping how enterprises design, deploy and monitor AI systems within automated workflows. Business leaders should familiarize themselves with these evolving standards through resources such as the European Commission's portal on AI regulation.

For investors and founders, the intersection of automation and AI is also creating new opportunities in vertical-specific platforms, from automated clinical trial management in life sciences to intelligent operations in renewable energy. Those tracking innovation and venture flows can follow developments in this space via innovation-focused coverage and broader technology analysis on business-fact.com, which contextualize these trends within public and private market dynamics.

Governance, Risk and Trust in Automated Enterprises

As automation becomes pervasive, issues of governance, accountability and trust take center stage. Stakeholders, including regulators, shareholders, employees and customers, are asking who is responsible when automated decisions lead to errors, biases or unintended consequences, and how organizations can ensure that automated processes remain aligned with policy, law and ethical norms over time.

Leading enterprises are responding by establishing formal automation and AI governance structures that mirror, and often integrate with, broader corporate governance. This typically includes clear ownership for automated processes, rigorous change management, independent validation and periodic audits. The Institute of Internal Auditors has issued guidance on auditing automated systems and AI, which can be accessed through its resources on emerging technology risk. These practices are increasingly seen as essential for maintaining investor confidence and regulatory compliance, especially in sectors such as finance, healthcare and critical infrastructure.

Trust is also shaped by transparency. Organizations that communicate clearly about how automation is used, what data is collected and how decisions are made are better positioned to build durable relationships with customers and employees. The OECD's principles on trust in digital environments provide a useful reference framework for policymakers and businesses alike. For companies operating globally, aligning automation practices with diverse regulatory regimes in Europe, North America and Asia-Pacific requires careful coordination between legal, compliance, technology and business teams.

For the business-fact.com readership, which includes investors, executives and entrepreneurs, this emphasis on governance and trust underscores that automation initiatives must be evaluated not only on financial metrics but also on their alignment with corporate values, risk appetite and long-term reputation. It also highlights why business-fact.com continues to track news and regulatory developments that influence how automation is deployed across industries and regions.

Automation, Sustainability and the Broader Economy

Sustainability has moved from a peripheral concern to a central strategic priority for enterprises in Europe, North America and increasingly in Asia, driven by regulatory requirements, investor expectations and societal pressure. Automation plays a critical role in enabling organizations to measure, manage and reduce their environmental footprint, as well as to support broader environmental, social and governance objectives.

Automated data collection and reporting systems allow companies to track emissions, energy consumption, waste and resource use across complex global supply chains, providing the granular visibility needed to meet standards such as the EU Corporate Sustainability Reporting Directive and frameworks from CDP and the Task Force on Climate-related Financial Disclosures. For a deeper understanding of these requirements and their implications for business, executives can consult resources from the European Environment Agency on corporate sustainability reporting. Automation is also being used to optimize energy usage in buildings, manufacturing plants and data centers, reduce material waste through precision manufacturing, and support circular economy models.

From an economic perspective, automation's impact on productivity, employment and inequality remains a subject of intense debate. Organizations such as the International Monetary Fund and the World Bank have produced nuanced analyses suggesting that while automation can displace certain categories of work, it also creates new roles and, when combined with effective education and labor market policies, can support inclusive growth. Those interested in the macroeconomic dimension can explore the IMF's research on technology and the future of work.

For business-fact.com, whose coverage spans sustainable business models, global economic trends and investment strategies, the key takeaway is that automation is now deeply intertwined with ESG performance and macroeconomic resilience. Investors are increasingly scrutinizing how companies use automation to support sustainability goals, manage workforce transitions and contribute to broader societal outcomes, rather than focusing solely on short-term cost savings.

Top Imperatives for Leaders in 2026 and Beyond

In this environment, executives, founders and boards need to approach automation as a long-term strategic capability rather than a discrete project. First, they must articulate a clear vision of how automation supports their business model, customer value proposition and workforce strategy, grounded in a realistic assessment of current capabilities and market conditions. Second, they should invest in the foundational elements of an automation-ready enterprise: high-quality data, modern cloud and integration architectures, robust governance frameworks and a culture that encourages experimentation and cross-functional collaboration.

Third, leaders must adopt a portfolio mindset, balancing near-term efficiency gains with longer-term bets on new products, services and markets enabled by automation and AI. This includes evaluating how automation intersects with other transformative trends, such as the rise of decentralized finance and digital assets, which are covered in business-fact.com's crypto and digital finance section, or the continuing digitization of marketing and customer engagement, explored in its marketing analysis. Finally, they must recognize that talent is as critical as technology; building a workforce that can design, manage and continuously improve automated systems will determine which organizations translate technological potential into durable competitive advantage.

As enterprises across the United States, Europe, Asia-Pacific, Africa and Latin America navigate a world characterized by geopolitical uncertainty, climate risk and rapid technological change, automation will be a defining factor in who thrives and who falls behind. For the readers of business-fact.com, the central message is clear: automation in 2026 is no longer primarily about cutting costs; it is about building resilient, innovative and trustworthy organizations that can compete and collaborate effectively in an increasingly complex global economy. Those who understand and act on this broader strategic agenda will shape not only the future of their own enterprises, but also the trajectory of industries and markets worldwide.